Professional Relative Strength Rotation Graph platform. Track momentum shifts across
symbols in real-time, spot RS-price divergences early, and trade with the rotation cycle.
Purchasing Power vs Gold · Daily / Prior-1…7 / Current · Leading/Lagging RRG quadrant
Inside the app · 1 of many
The Relative Rotation Graph
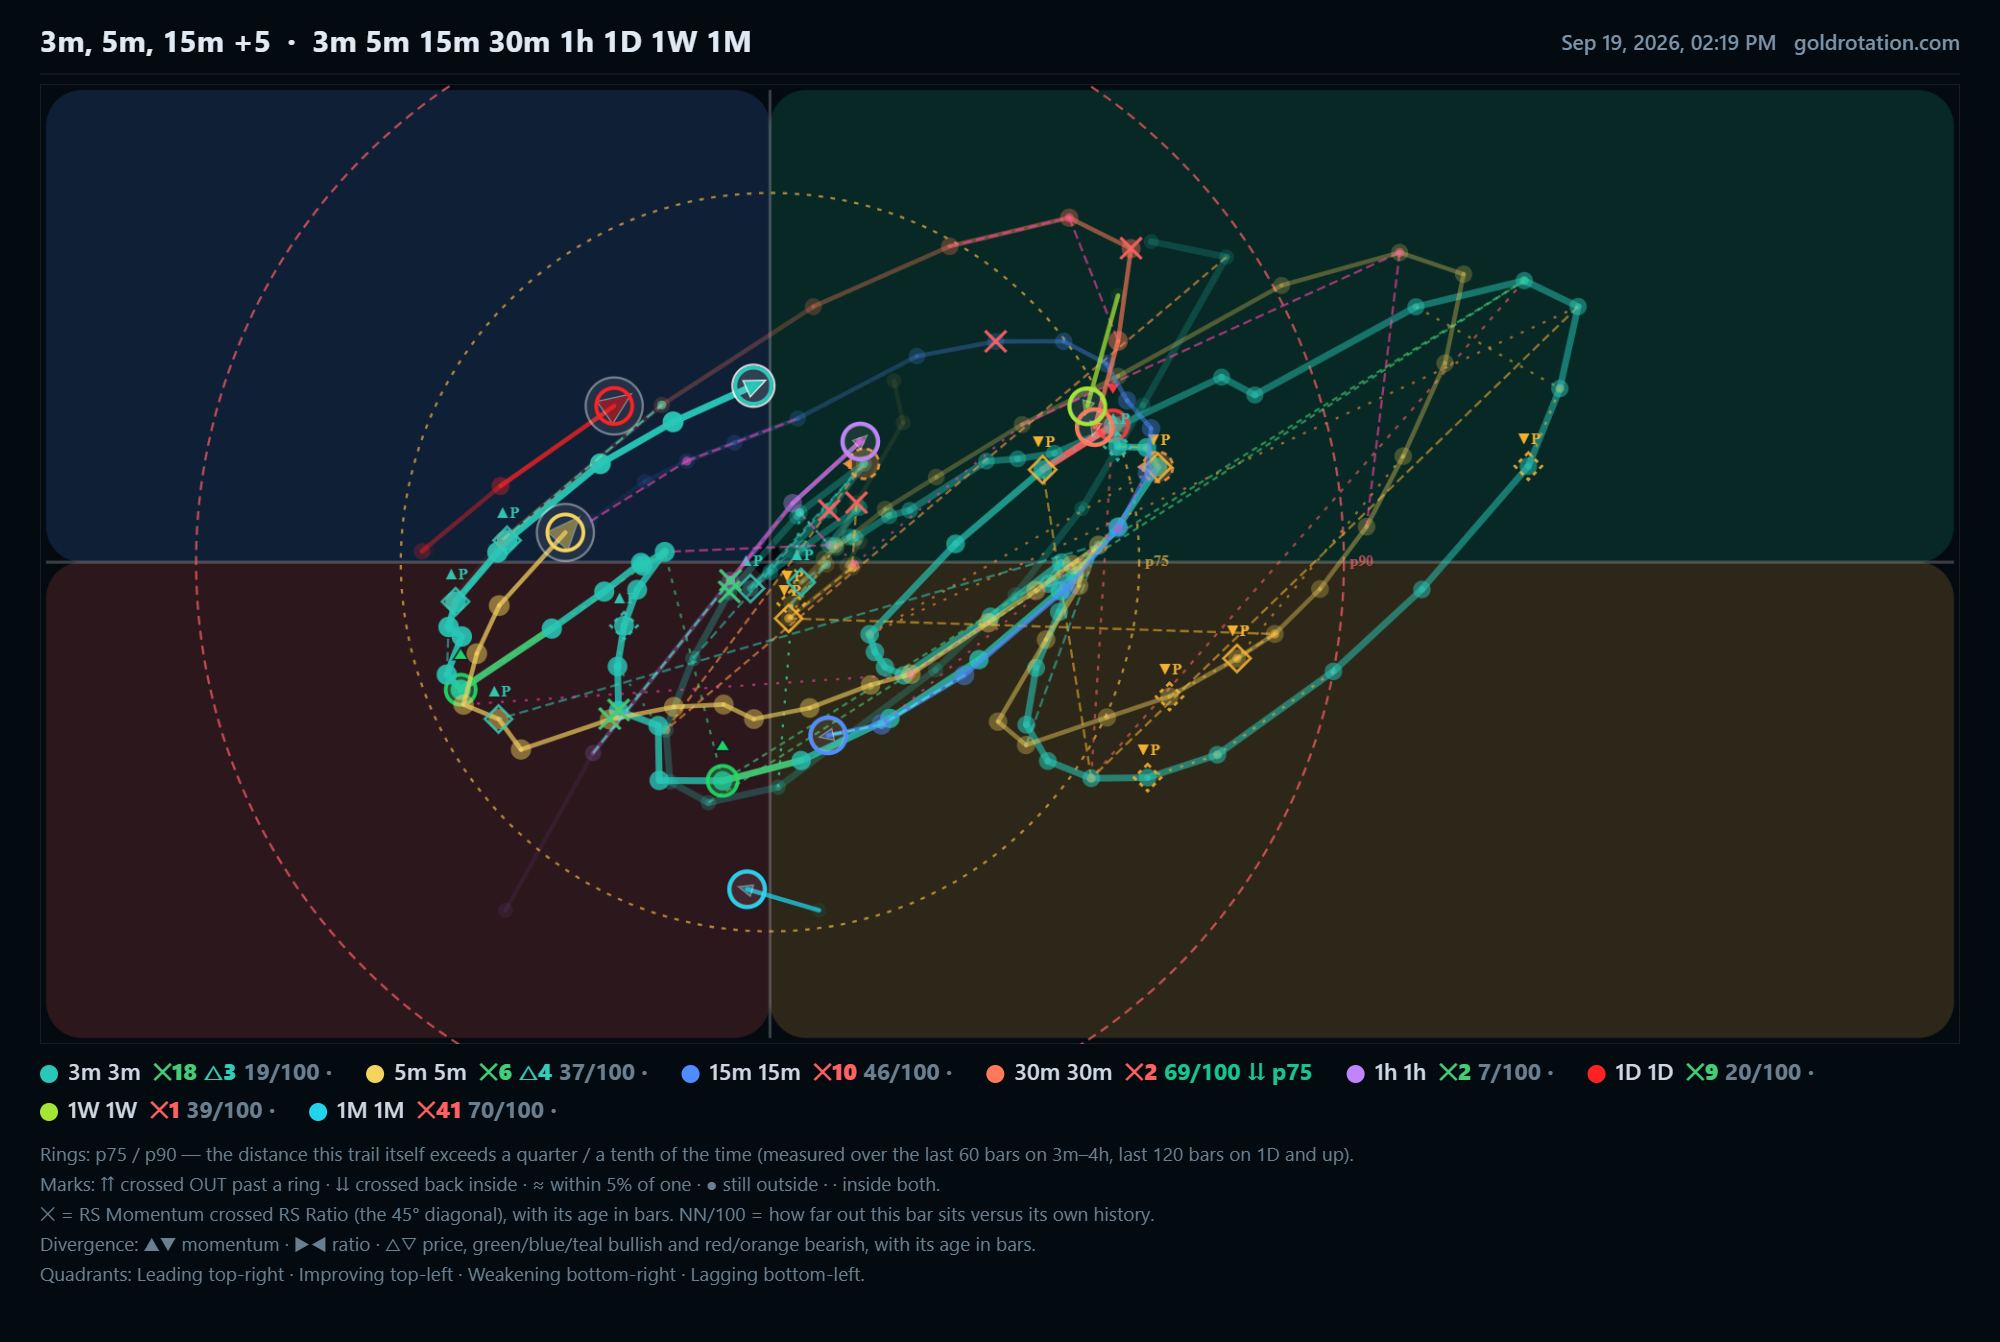
Every timeframe from 3 minutes to 1 month rotates around the same centre at once, each as its own
trail. The picture below is not a mock-up: it is an export straight out of the app, carrying the
same key you get when you copy it.
Exported with the Copy button — header, per-timeframe readings and key included.
Snapshot not published yet — export one from the app and save it as assets/landing/rrg.png.
Every timeframe at once
3m, 5m, 15m, 30m, 1h, 4h, 1D, 1W and 1M each draw their own trail on one plane, so a move that
has already turned on the hourly but not on the daily is something you see rather than infer.
Overbought and oversold, measured honestly 69/100
Distance from the centre has no fixed ceiling, so a fixed threshold would be invented. Each
reading is a percentile against that trail's own recent history instead — 90 means further out
than nine tenths of its own past, on the strength side or the weakness side.
Bands you can see p75 · p90
Two dashed rings sit at the distances that trail itself exceeds a quarter and a tenth of the
time — the rotation's answer to the 70 and 30 lines, drawn from data rather than convention.
Crossings, not guesswork ⇈ ⇊ ≈ ●
Each timeframe says whether it has just crossed a band outward, fallen back inside, is within
five per cent of one, or is still outside — with the age of that event in bars.
The rotation's own turn signal ✕
When relative momentum crosses relative strength — the plane's 45° diagonal — the rotation has
stopped falling or stopped rising. It usually prints before the quadrant changes.
Divergence on three axes ▲▼ ▶◀ △▽
Momentum, ratio and price divergences are detected on every timeframe and marked where they
happened, with direction as colour and age in bars, so nothing depends on spotting it yourself.
Price, at the node you are asking about
Click any node and the candles around that bar open beside it. The chart and the price series
stay tied together: a range picked on one is the range read on the other.
A picture that explains itself
Copy or download the chart and it leaves with a header, each timeframe's reading, the mini price
chart and the key to every mark — so the person you send it to can read it without you.
Divergence alerts, GOLD/OIL signals and Fibonacci overlays get their own sections next.
Inside the app · 2 of many
Sovereign yield curves & spreads
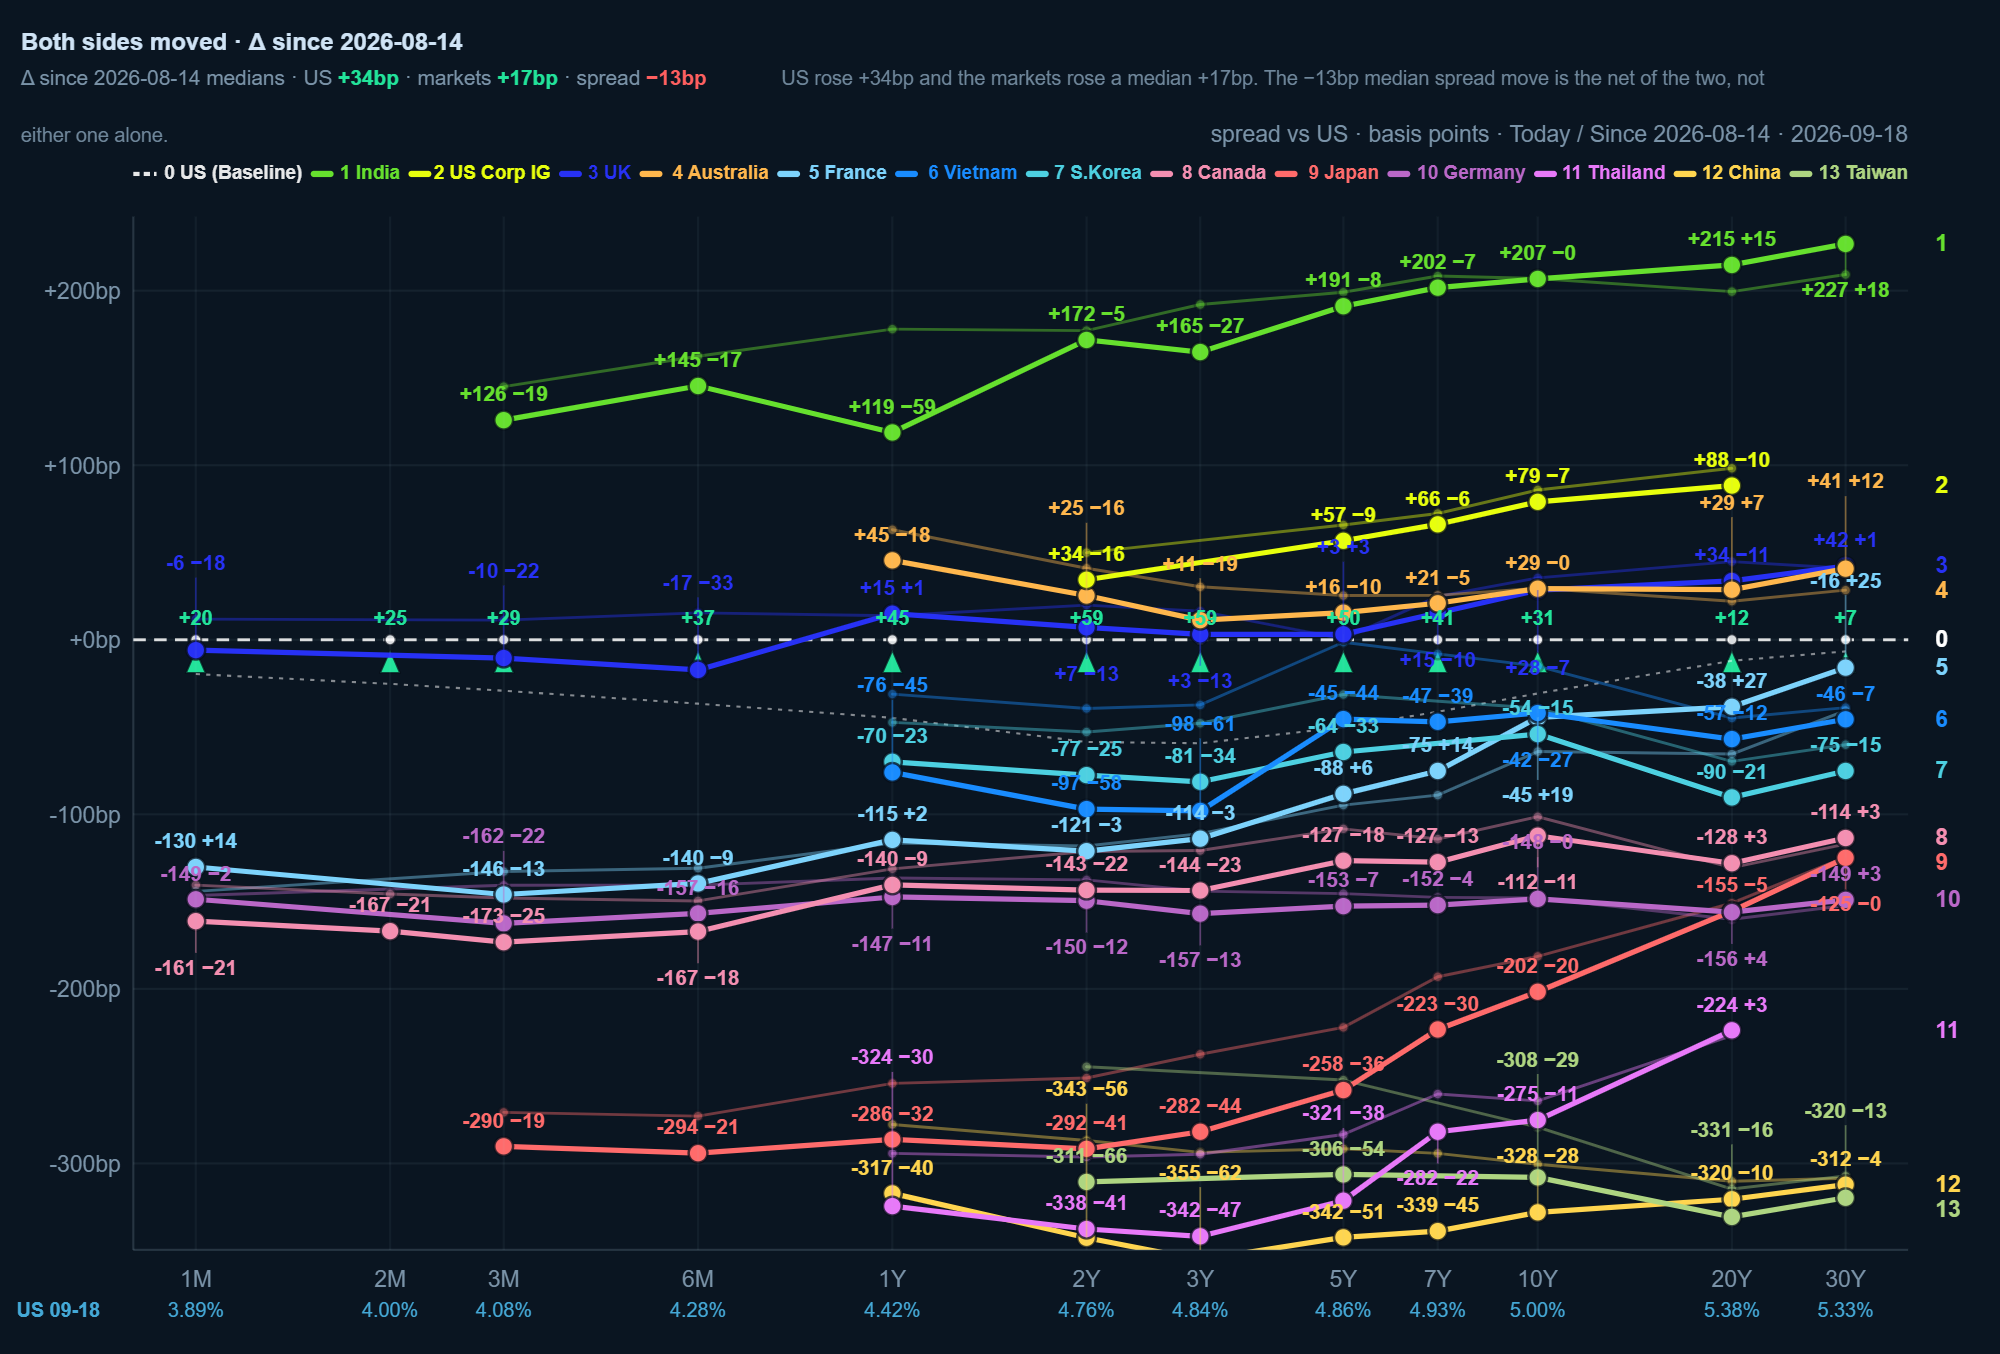
Every ticked market's curve minus the base country's, in basis points, at today's close
and a week and a month back — so a carry is something you read off the chart rather than
work out. This picture, too, comes straight from the app.
Exported with the same Copy button — the caption inside names the country, the unit and the dates.
Curve not published yet — open the bond page and press Publish.
Spread, not two charts side by side
Pick a base country and every other market is drawn as its difference from it, in
basis points. The height of a line is the carry you would earn funding there.
Widening or closing, on the same axes
Today's curve is drawn with the same curve a week and a month ago. A line sitting
under its own month-old shape is a spread compressing — no second chart needed.
Matched by date, never by bar count
Two countries keep different holidays, so lining their series up by position invents
moves that never happened. Legs are paired by trading date, and a maturity a market
does not issue is left out rather than drawn empty.
Who moved, not just how much Δ
A spread widening says nothing about which leg moved. Each node can carry its own
one-day change with the base country's move underneath, since d(spread) = d(market) − d(base).
Every maturity a market really has
The curve's x-axis is built from that country's own issues, verified rather than
assumed — so a market with no bill under a year simply has no 3M point.
Checkable line by line
The CSV carries both legs of every spread, the symbols they came from and the date
each was read at, so the arithmetic can be redone by hand instead of trusted.
Inside the app · 3 of many
The gold-adjusted heatmap
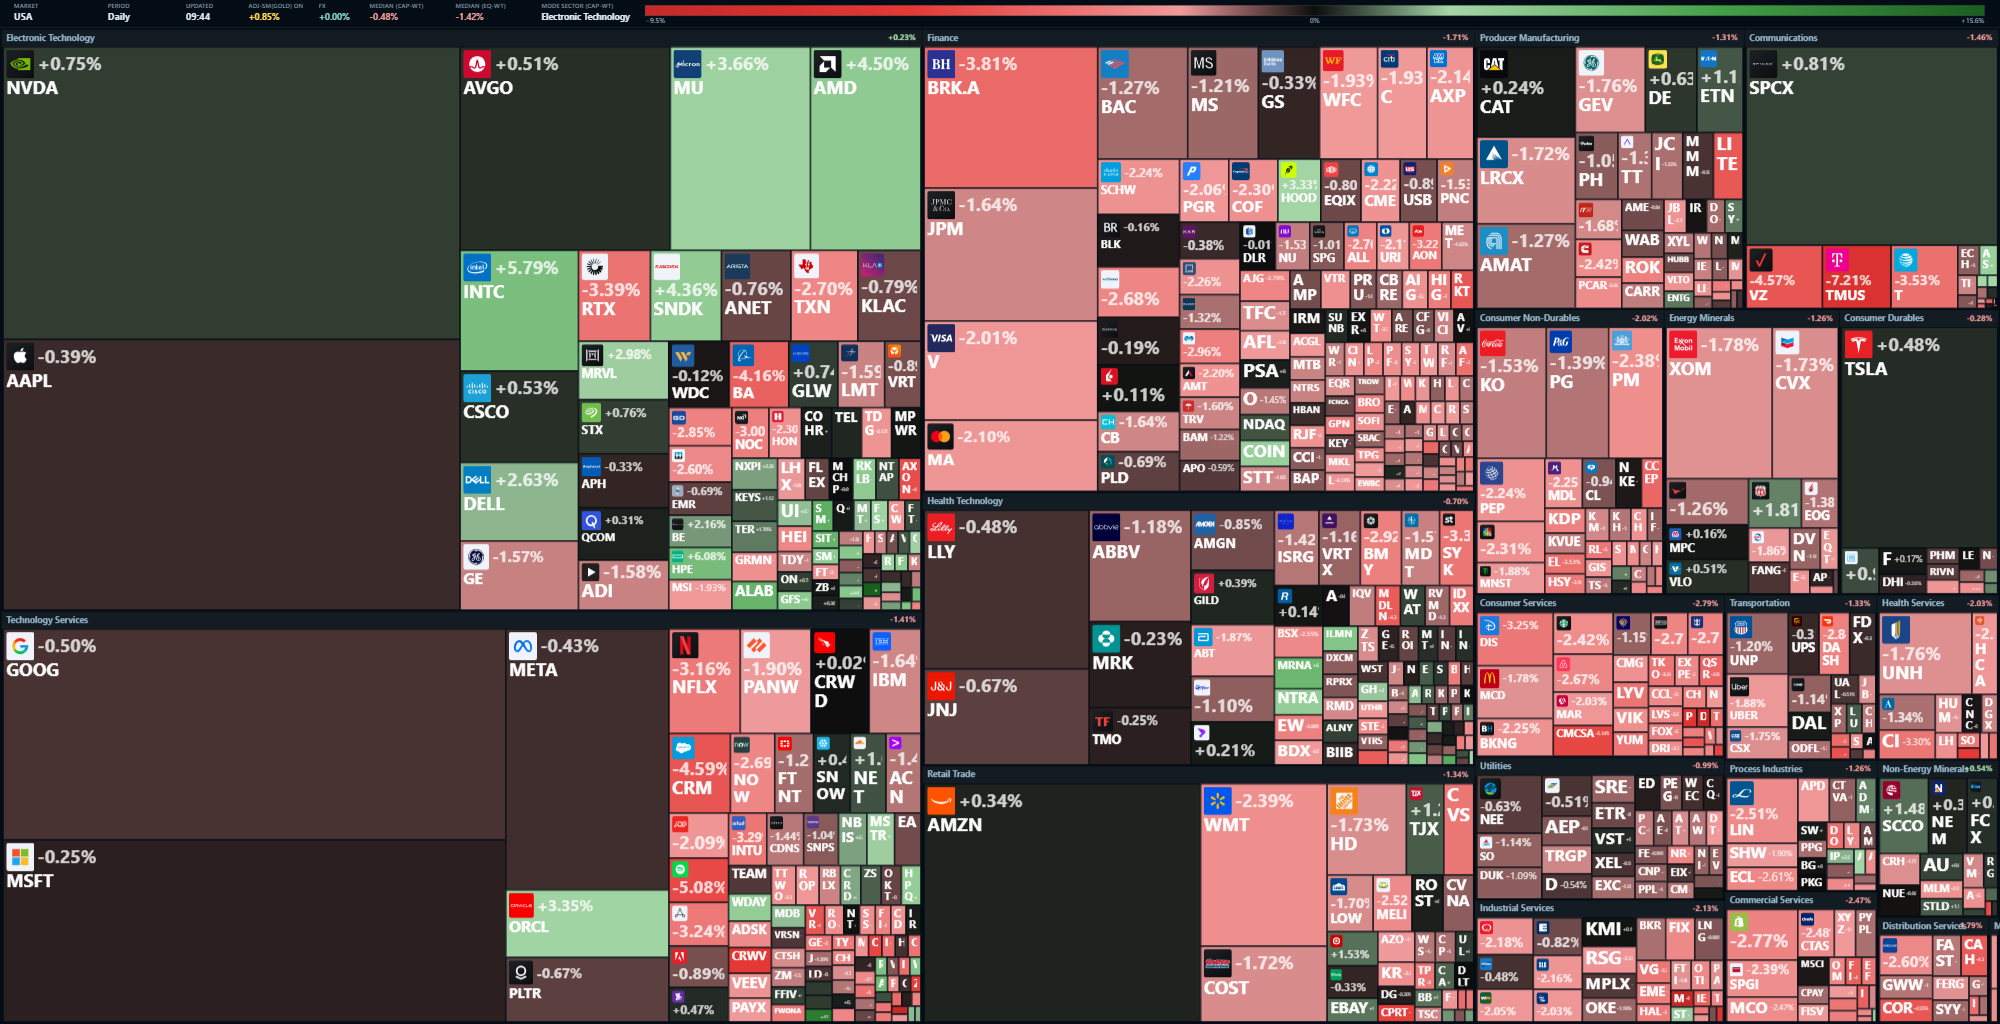
Thousands of stocks across sixteen markets, sized and coloured by what they did — and
priced in gold, not in the currency they happen to trade in.
Exported with the heatmap's own Copy button, at the resolution set beside it.
Heatmap not published yet — open the app and press Publish above the heatmap.
Priced in gold, by default
A stock up 4% in a currency that lost 5% against gold did not gain anything. Every
tile is adjusted by that market's own gold price in its own currency, so markets can
be compared at all — with a No-Gold switch when you want the raw move.
Sixteen markets, one grid
US, Europe, Asia and the rest sit side by side, grouped by market, sector or
industry, filtered by size, and searchable — the same picture whichever way you cut it.
Any horizon, not just today
Daily, month-to-date, a week, a quarter, a year, five years, or since inception —
and RS ratio, momentum and quadrant for the rotation view of the same board.
Live, without pretending
An optional intraday pass compounds today's move onto the settled figure. When a
market has not given one back, the tile says it is showing the stored reading and
when it was stored, rather than quietly printing a zero.
Straight into the rotation graph
Whatever the filters leave on screen can be sent to the rotation graph or the
scanner in one click, so a question that starts on the heatmap finishes on the chart.
Exports at the size you need
Pick the pixel width and the scale; the picture is redrawn at that size rather than
stretched, so a 2000px export is genuinely more detail.
Inside the app · 4 of many
Global equities, two measures at a time
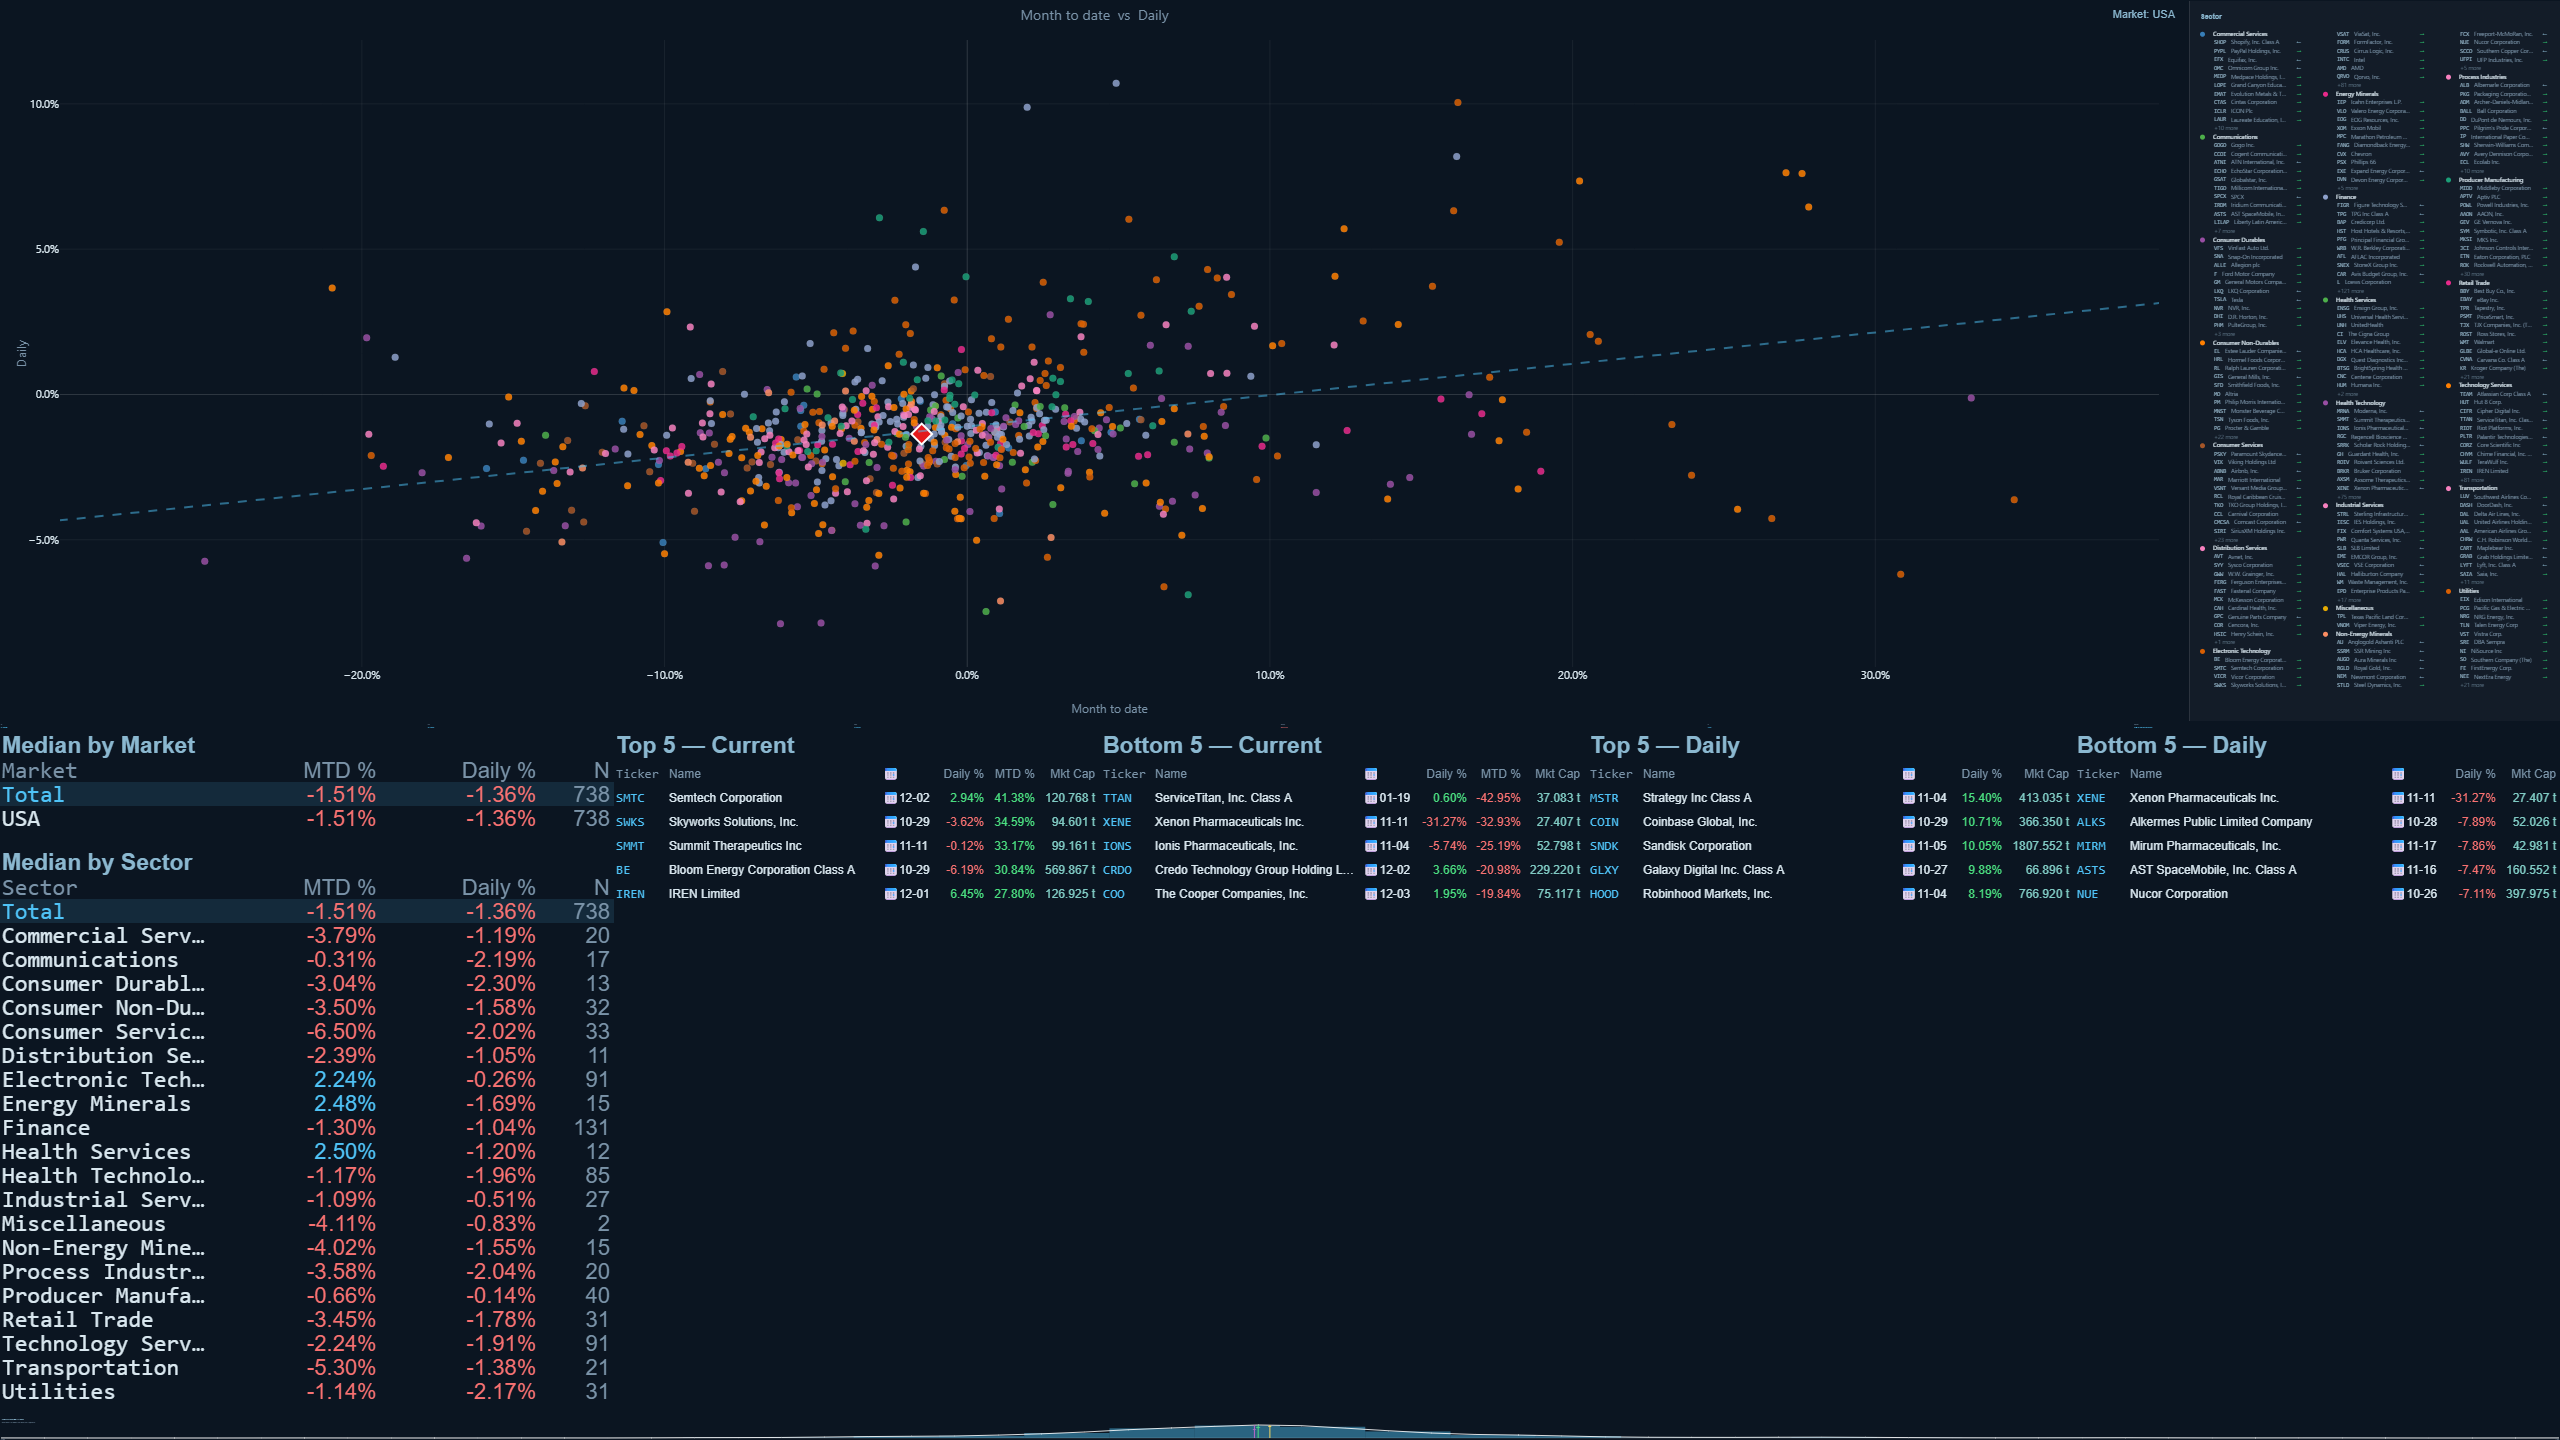
Any two things a company can be measured by, plotted against each other across the whole
board — with the line through them, how well it fits, and who sits furthest from it.
Exported with the chart's own Copy button — legend, statistics and median blocks included.
Chart not published yet — open Global Equities and press Publish.
Pick both axes
Performance over any horizon, valuation, growth, margins, size — choose what goes on
each axis and the whole board is replotted against it.
The fit, stated R² · slope
The regression line comes with its R², correlation, slope, intercept and sample size
printed beside it, so "these two move together" is a number rather than an impression.
Size is a third measure
Points can be sized by market capitalisation or by any other field, which is often
where the story is: a cluster of small names and one enormous outlier are not the same
finding.
Pin what matters
Click a point to pin it. Pinned names travel into the exported picture in their own
panel, so the chart you send carries the companies you were actually talking about.
Medians and extremes, per cut
Median lines per sector or market, the top and bottom names by each axis, and a
distribution of the plotted measure — all optional, all in the export.
The data, not just the picture
One click downloads exactly what is plotted — both axes, the daily move and the market
cap per stock, plus the ranking tables — under the filters showing at that moment.
Inside the app · 5 of many
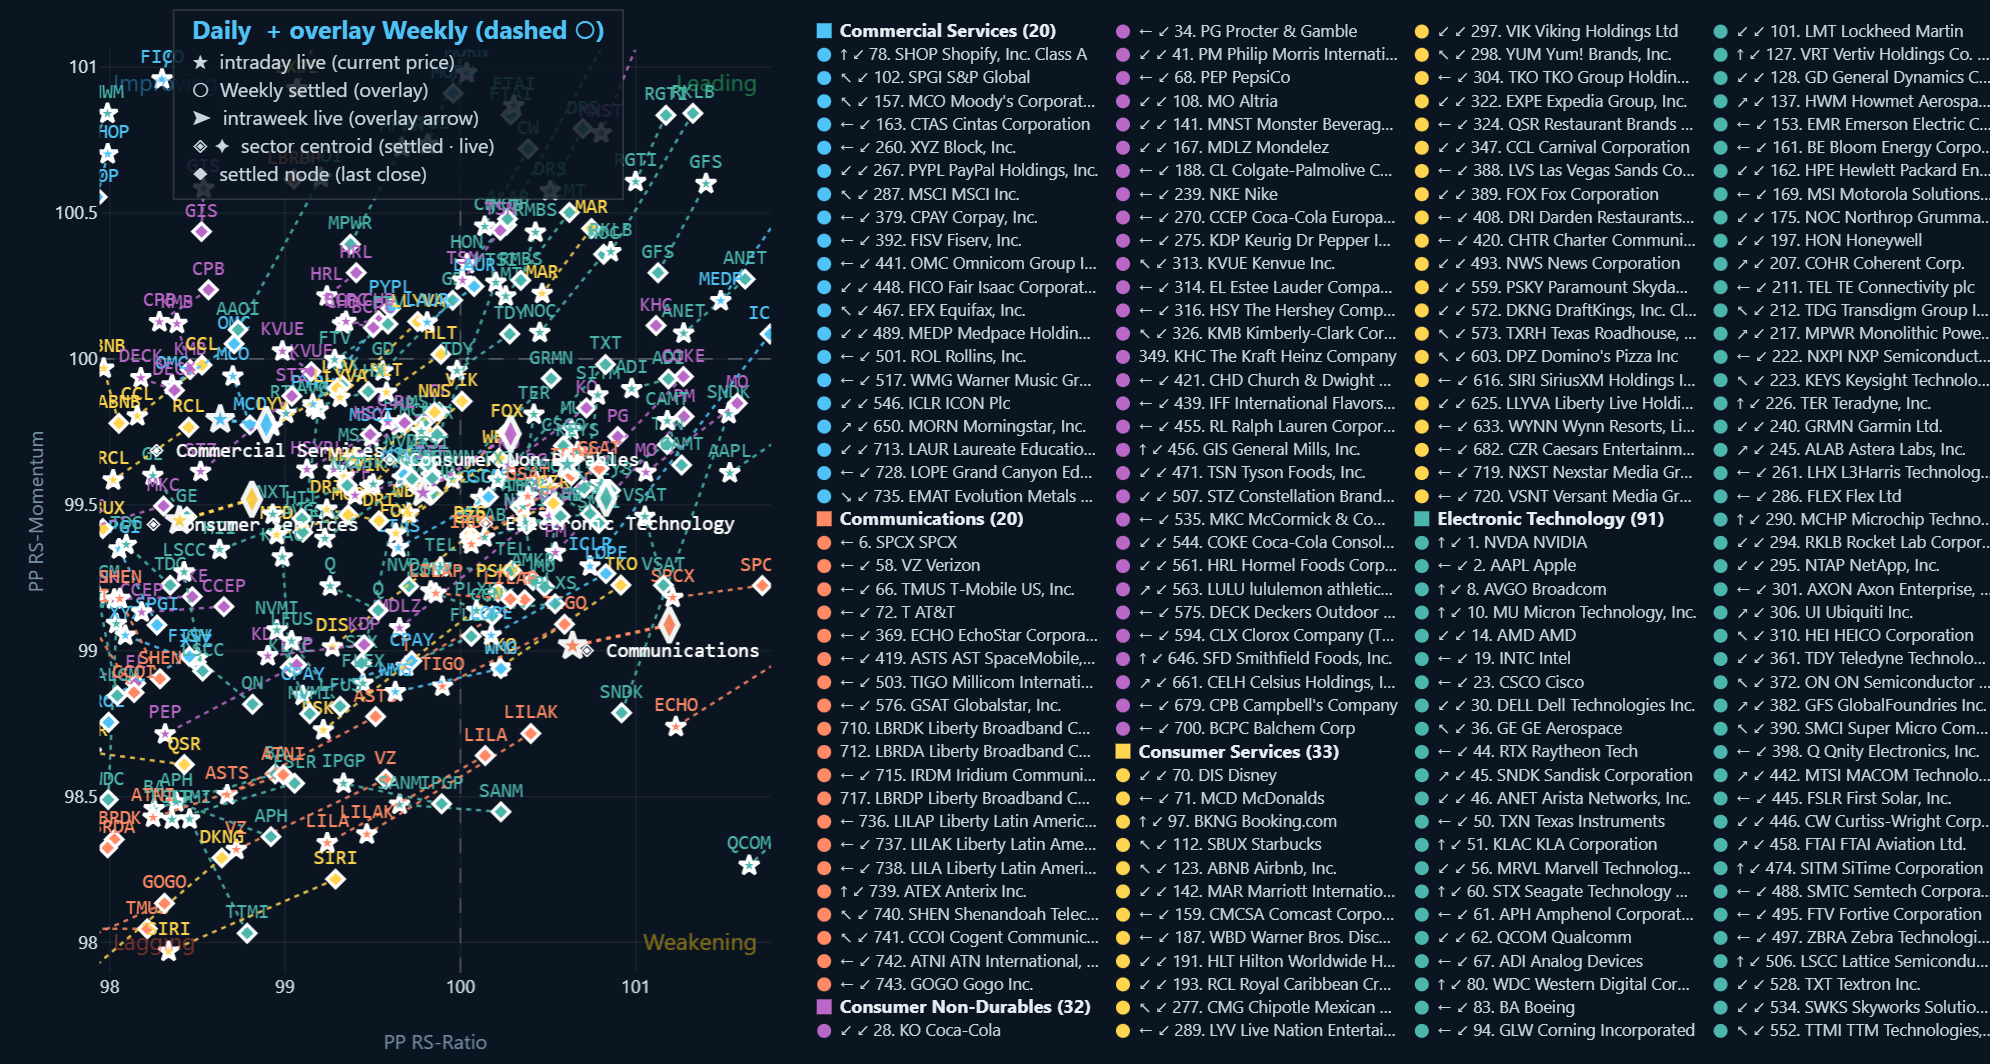
Purchasing-power rotation
The same rotation, but the benchmark is gold. Hundreds of stocks at once, each plotted by
what it buys rather than what it costs — with sector centroids showing where the money is
going as a group.
Exported with its own Copy button — the sector key travels with the chart.
Not published yet — open the PP rotation graph and press Publish.
Measured in gold, not in currency
Each stock's purchasing power is its price divided by gold in that market's own
currency, so a market whose money is falling cannot look strong just because its
index is rising.
Hundreds of names, not a handful
A whole board can be plotted at once, straight from the heatmap or the scanner, and
the trails stay readable because the axes normalise per symbol.
Sectors as a centroid
Each sector's cap-weighted centre is drawn with the names, so rotation between
sectors is visible without reading forty trails one at a time.
Intraday without the cap
An optional bulk pass adds today's move to every plotted symbol at once, through the
screener rather than a quote per stock, so the board is current without hundreds of
requests.
Inside the app · 6 of many
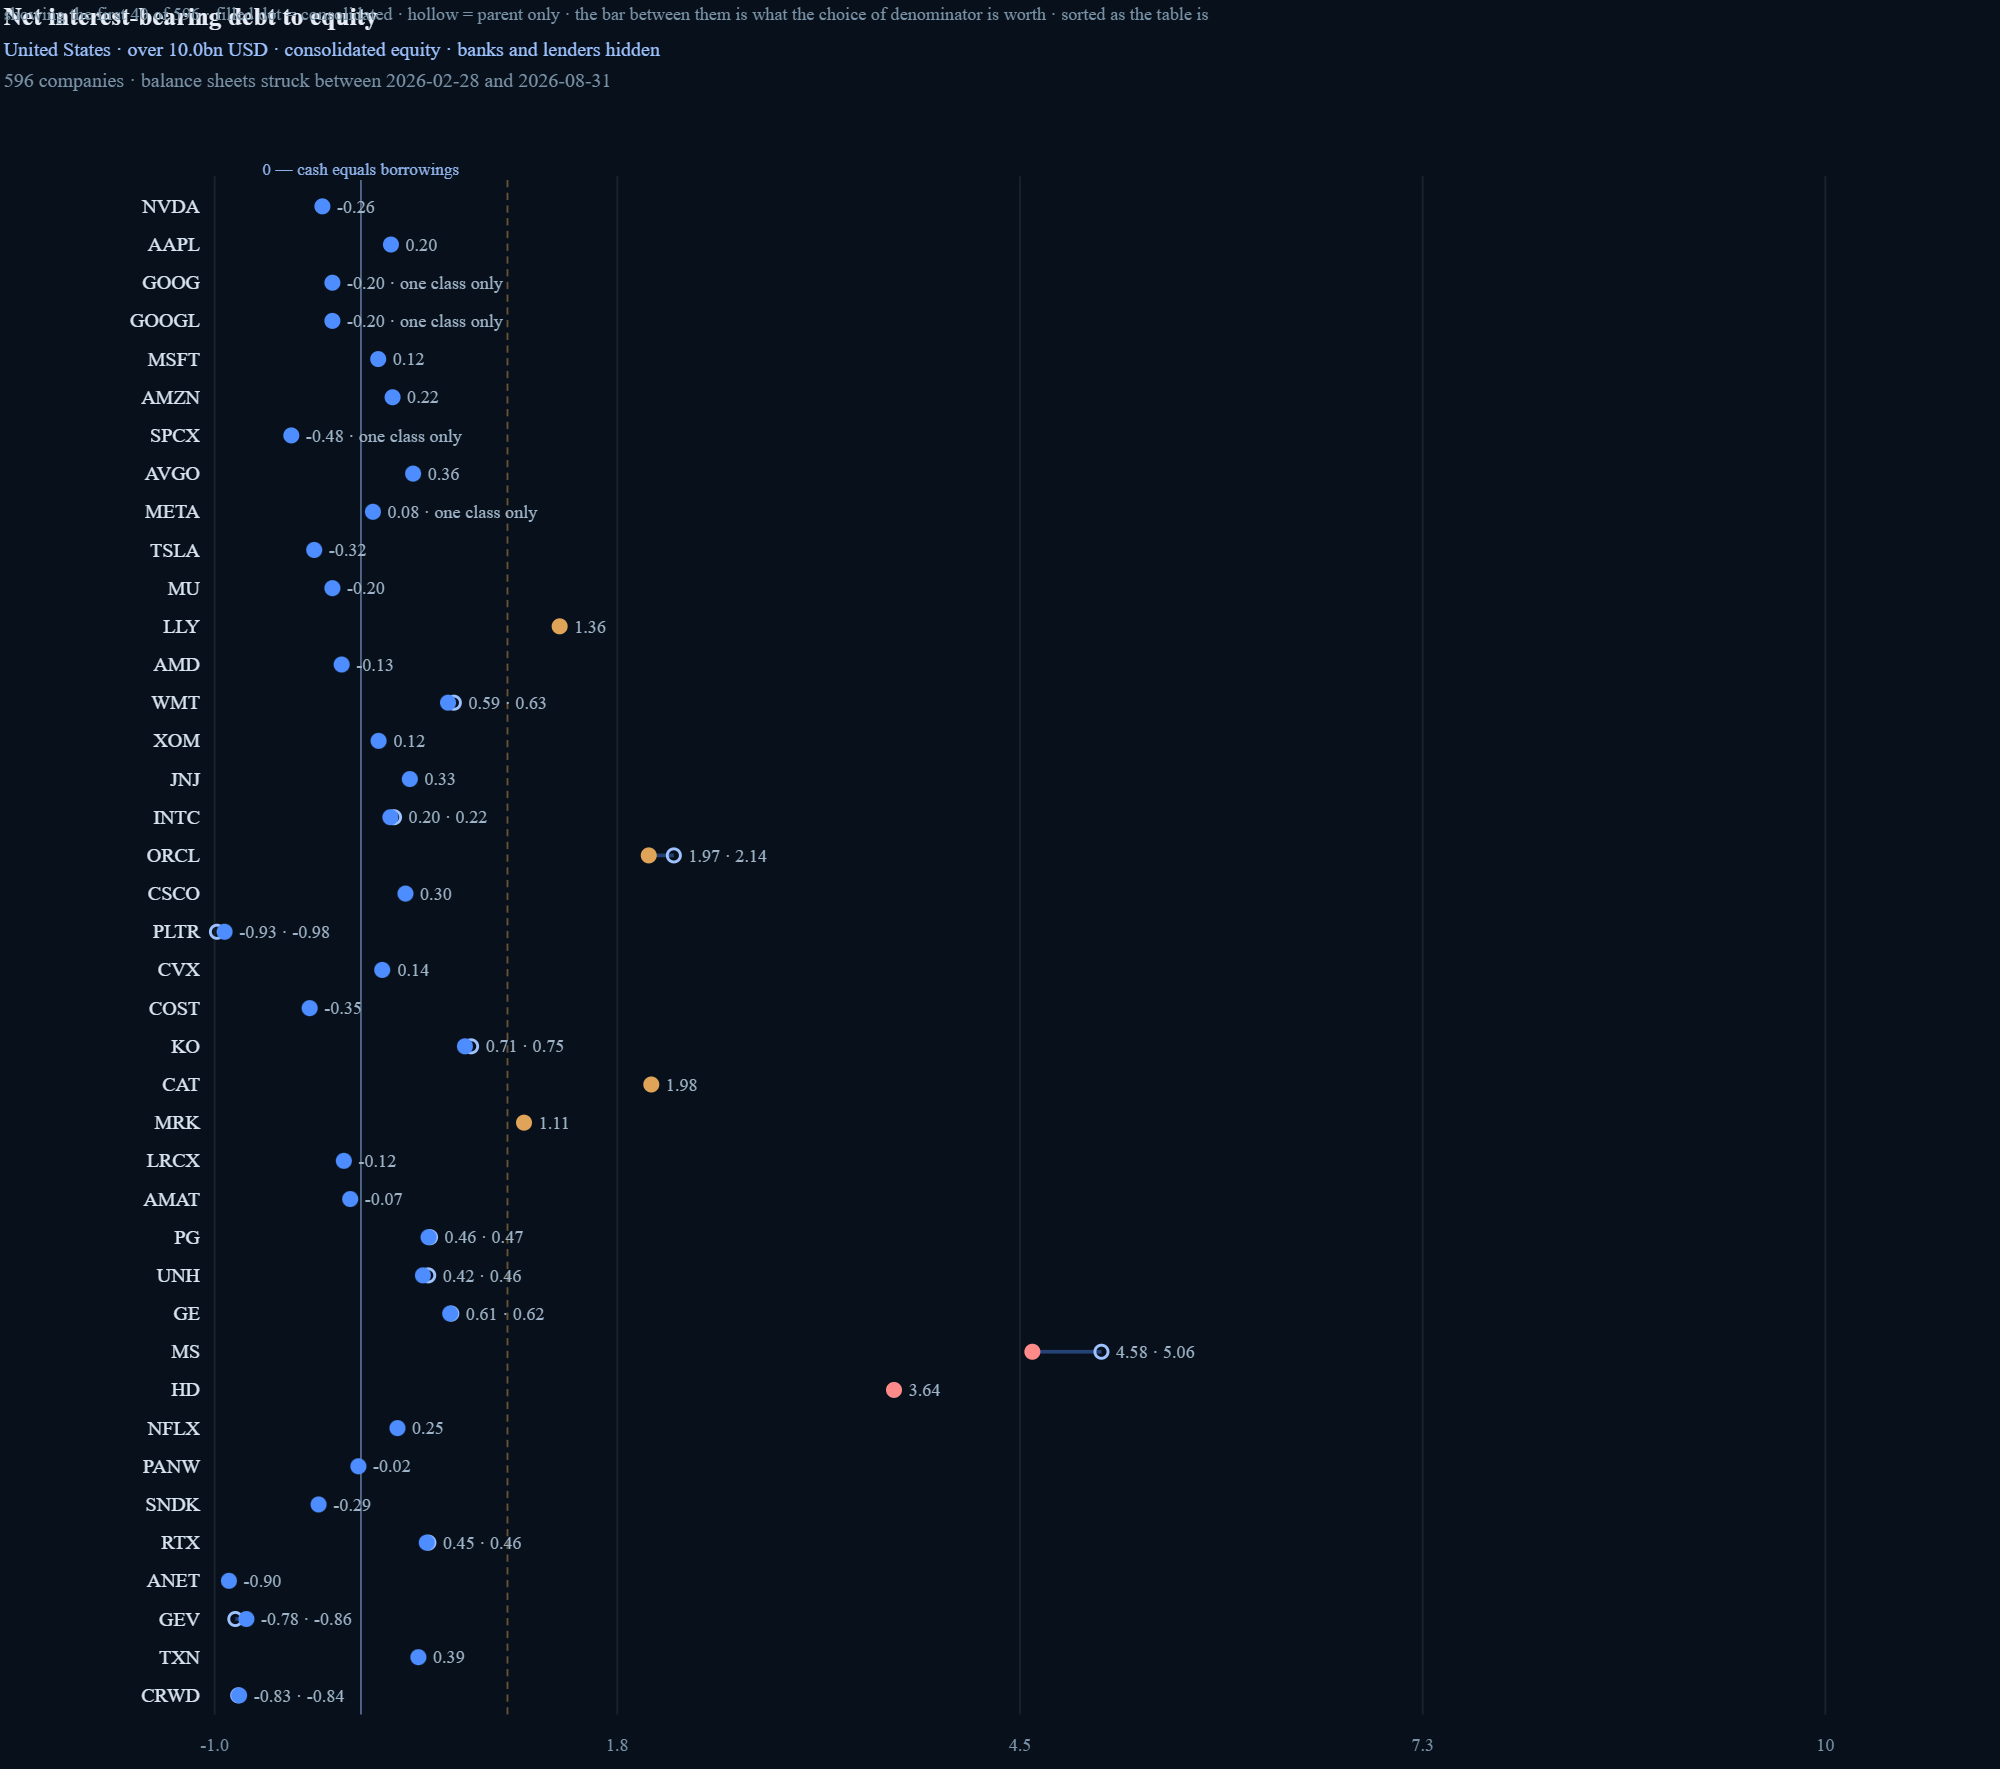
Net interest-bearing debt to equity
How much of a market runs on borrowed money — company by company, and the same market a
quarter or a decade ago, so leverage is read as a trend rather than a snapshot.
Exported with the page's own Copy snapshot button, at the layout width set beside it.
Not published yet — open the gearing page and press Publish.
Net, and interest-bearing
Cash is netted off and only debt that charges interest is counted, so the figure is
what the balance sheet actually owes rather than the sum of everything labelled
liability.
A whole market in one picture
Every company in the chosen market is ranked together, which is where the outliers
show: one borrower at four times equity among peers at half.
History, not just today
The same market can be redrawn at past quarters, so a company levering up is
distinguishable from one that has always been levered.
Exported at the size it is read
The preview draws the chart at the exact shape the snapshot will have — header rows
and all — so what is on screen is what the picture gives you.
Inside the app · 7 of many
Corporate bonds, seven ways
What a company borrowed, what it pays for it, when it has to find the money again, and whether
the equity is priced as if it will. Seven pictures, each from the same page, each with what it
answers underneath it.
1 of 7
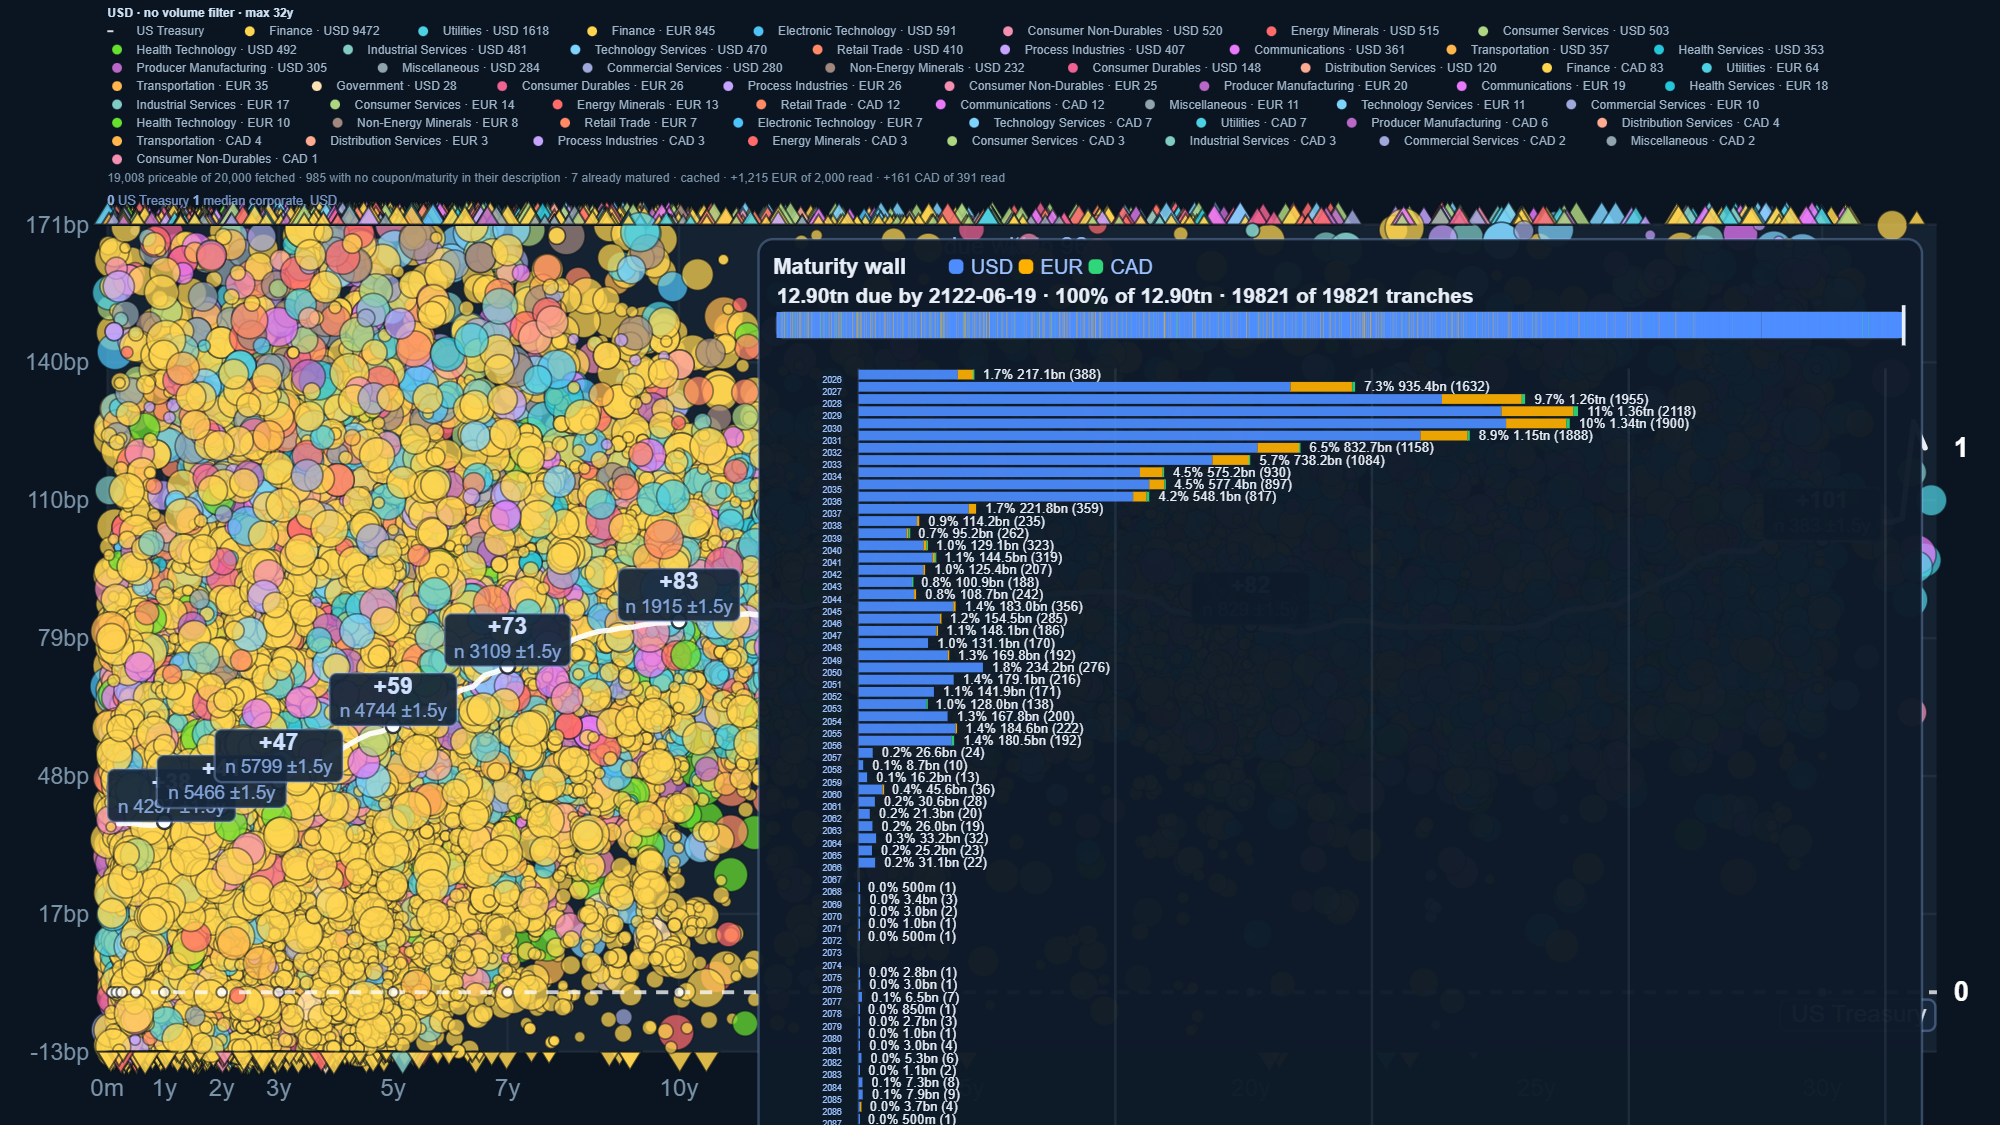
Yield against the Treasury curve
Every bond on the board as a dot at its maturity and its yield, with the government curve of the same currency drawn through them. The vertical gap between a dot and that line is the spread: what the market charges this borrower, over the state, for money of that length, today.
Sized by what is outstanding, so a $5bn benchmark and a $50m tap are not the same dot.
Tag a company and its issues take a colour of their own while the rest of the board stays grey behind them.
The curve is the right one: a euro bond is measured against a euro government curve, never a Treasury one.
Not published yet — picture: the scatter
2 of 7
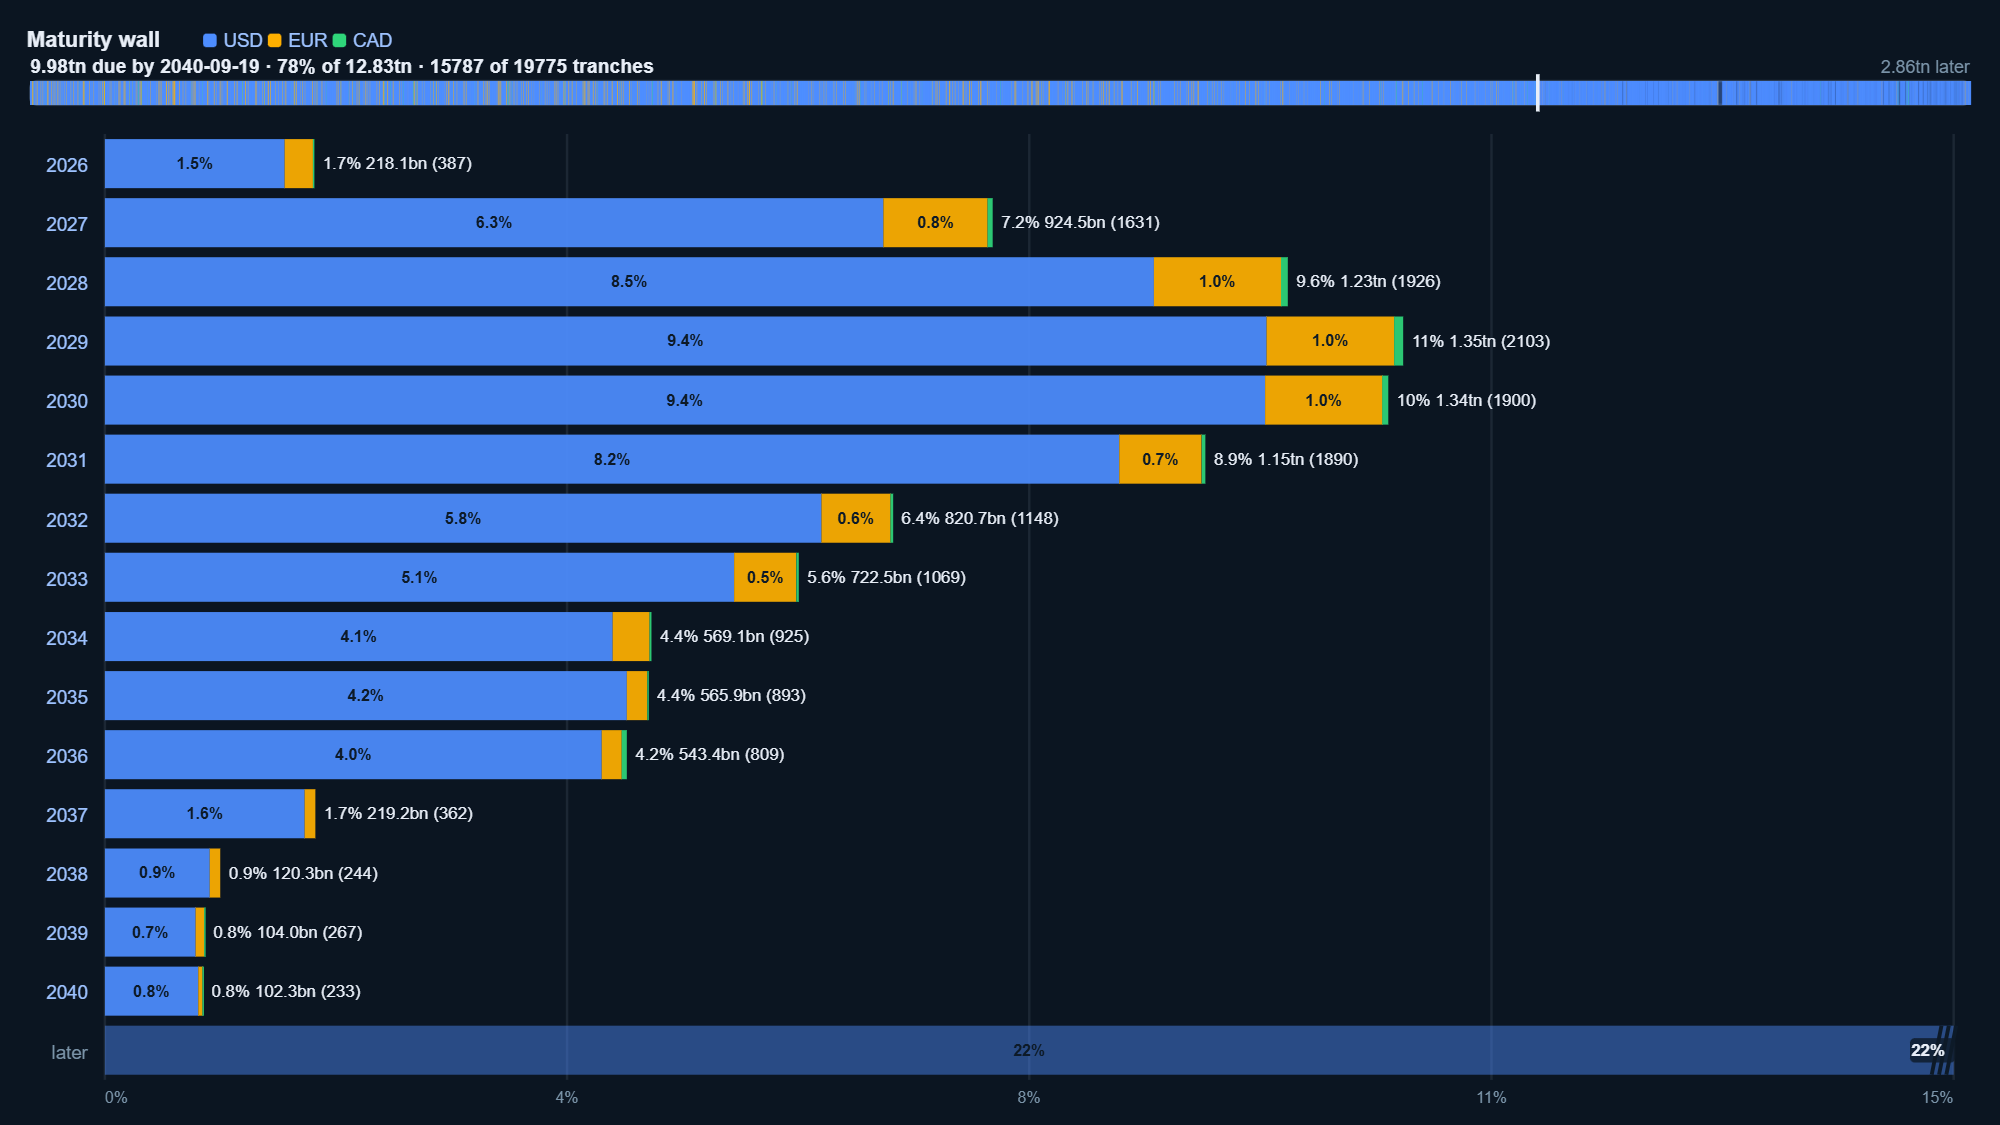
The maturity wall
How much has to be repaid in each year ahead, stacked by issuer and split by currency. It is the question a spread cannot answer: not what the debt costs, but when the company has to find the money again.
A convertible counts at its put date, not its maturity — that is the day holders can ask for cash.
Each bar carries its share of the total and the number of tranches behind it, so one enormous year is distinguishable from many small ones.
Currencies stay separate rather than being converted into one and losing the fact that the money has to be found in each.
Not published yet — picture: the maturity wall
3 of 7
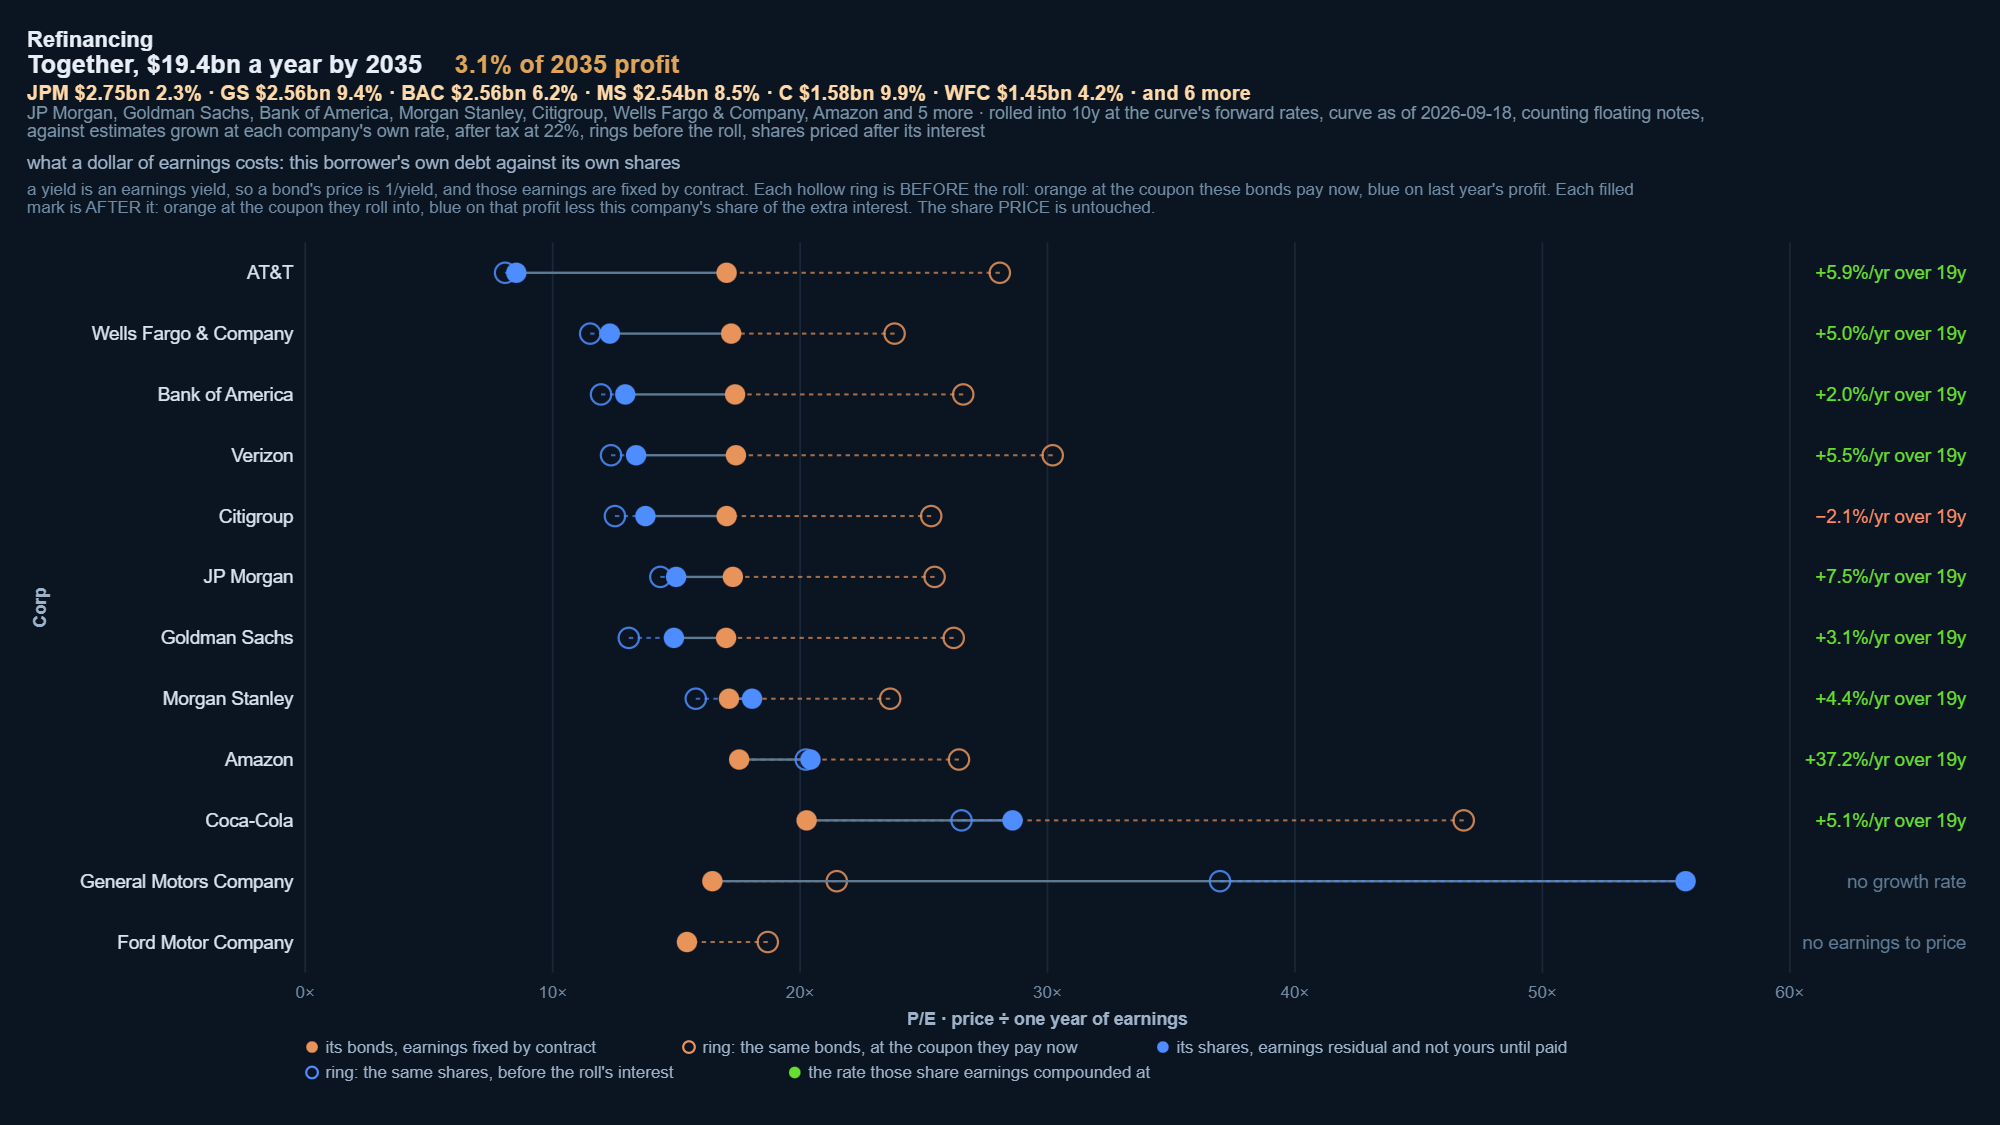
Refinancing
What each year's maturing debt costs now, against what the same money would cost at today's curve. The difference is the interest bill that arrives if the debt is rolled rather than repaid.
Rolled at this borrower's own spread, at whatever tenor you choose, with a shock you set in basis points.
Measured against earnings, so the answer is a share of profit rather than an abstract number of millions.
Debt the board does not list — bank loans, commercial paper, leases — can be rolled with the bonds or repriced at once, because what it does is an assumption and it is yours.
Not published yet — picture: refinancing
4 of 7
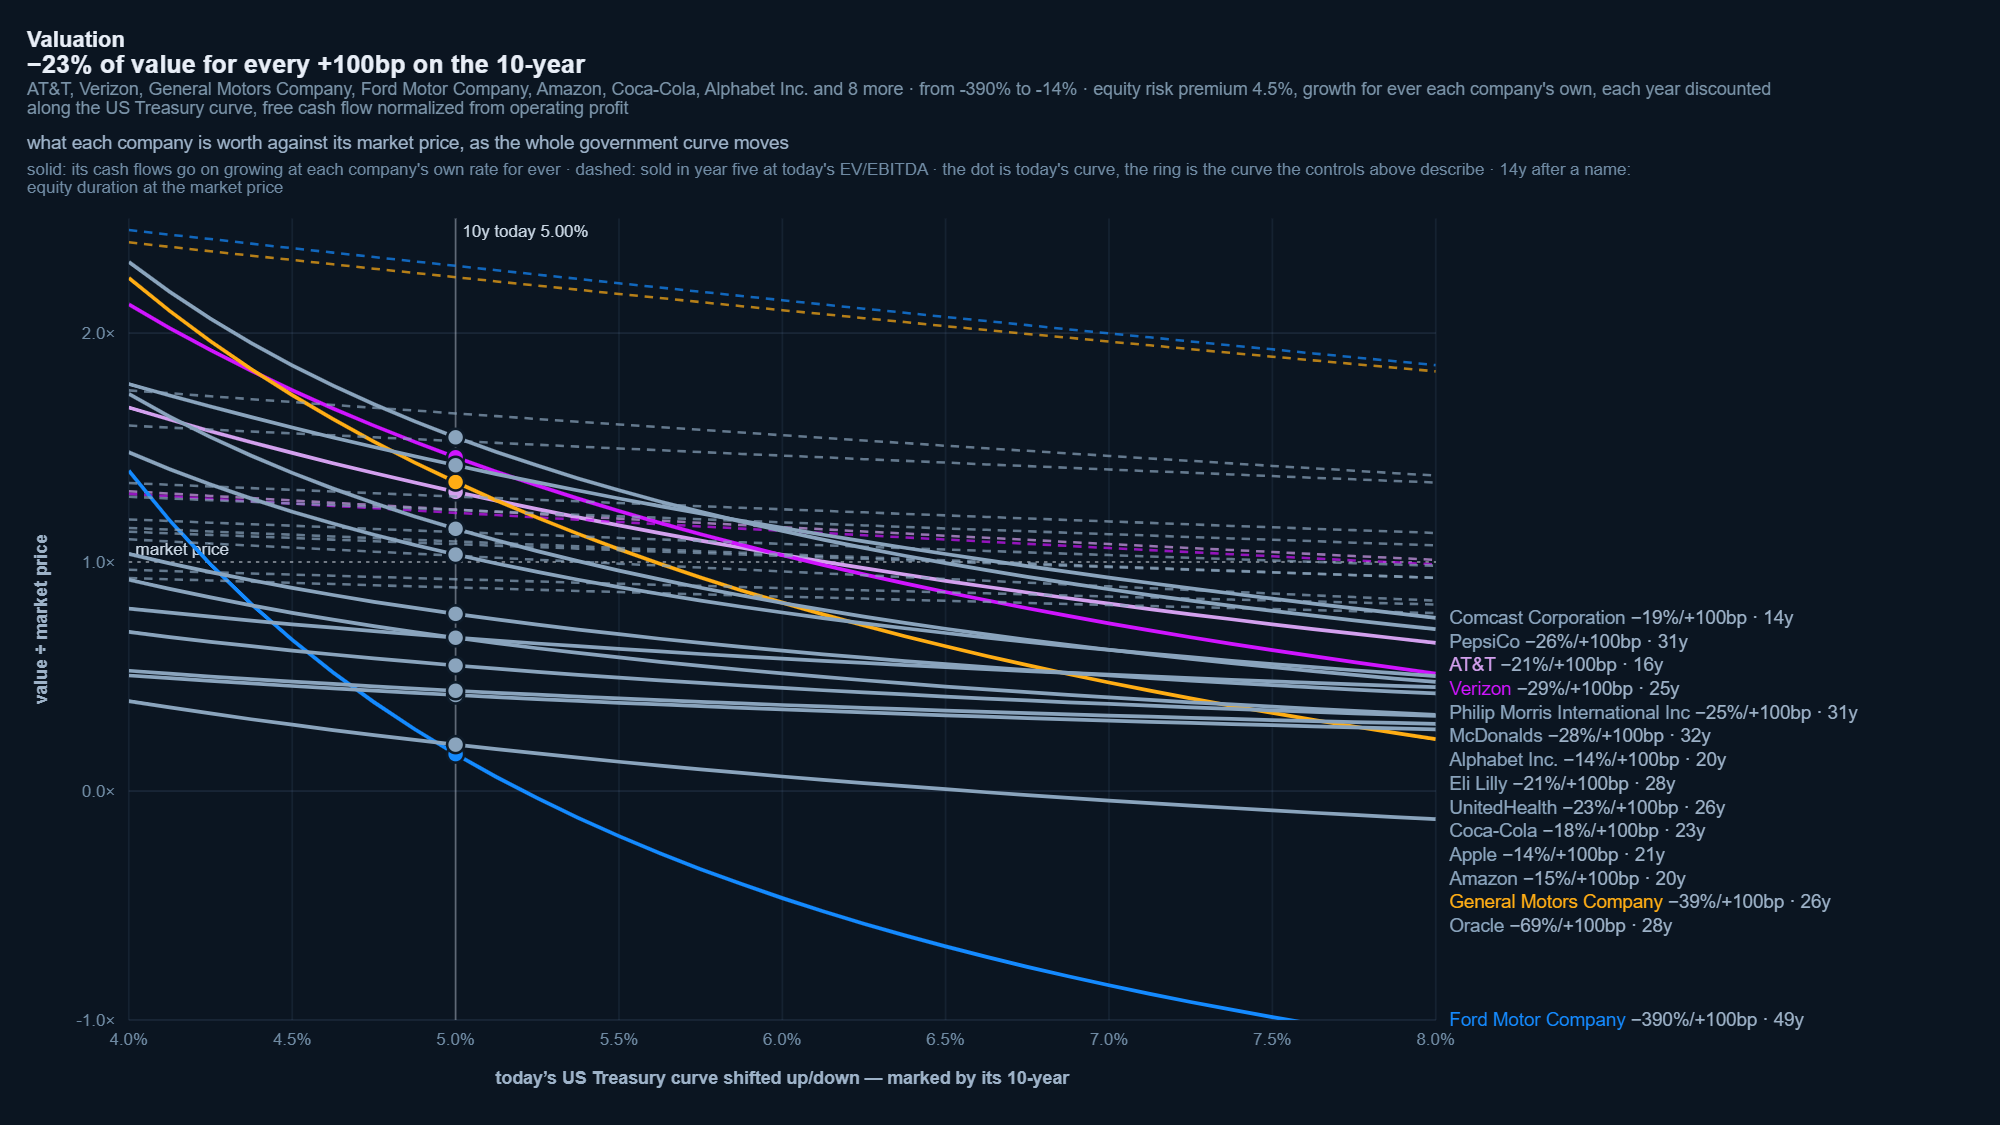
Valuation
The equity discounted on its own cash flows, with every assumption printed on the picture rather than buried behind it — the discount rate, the growth, the terminal figure, and what each is doing to the answer.
A normalised variant for companies whose last year was not a normal one, so one bad quarter does not become a permanent verdict.
Sensitivity in the picture: the value against the rate and the growth, so \u201cwhat would have to be true\u201d is read off rather than argued.
Says when it cannot value something and why, instead of printing a number it does not believe.
Not published yet — picture: valuation
5 of 7
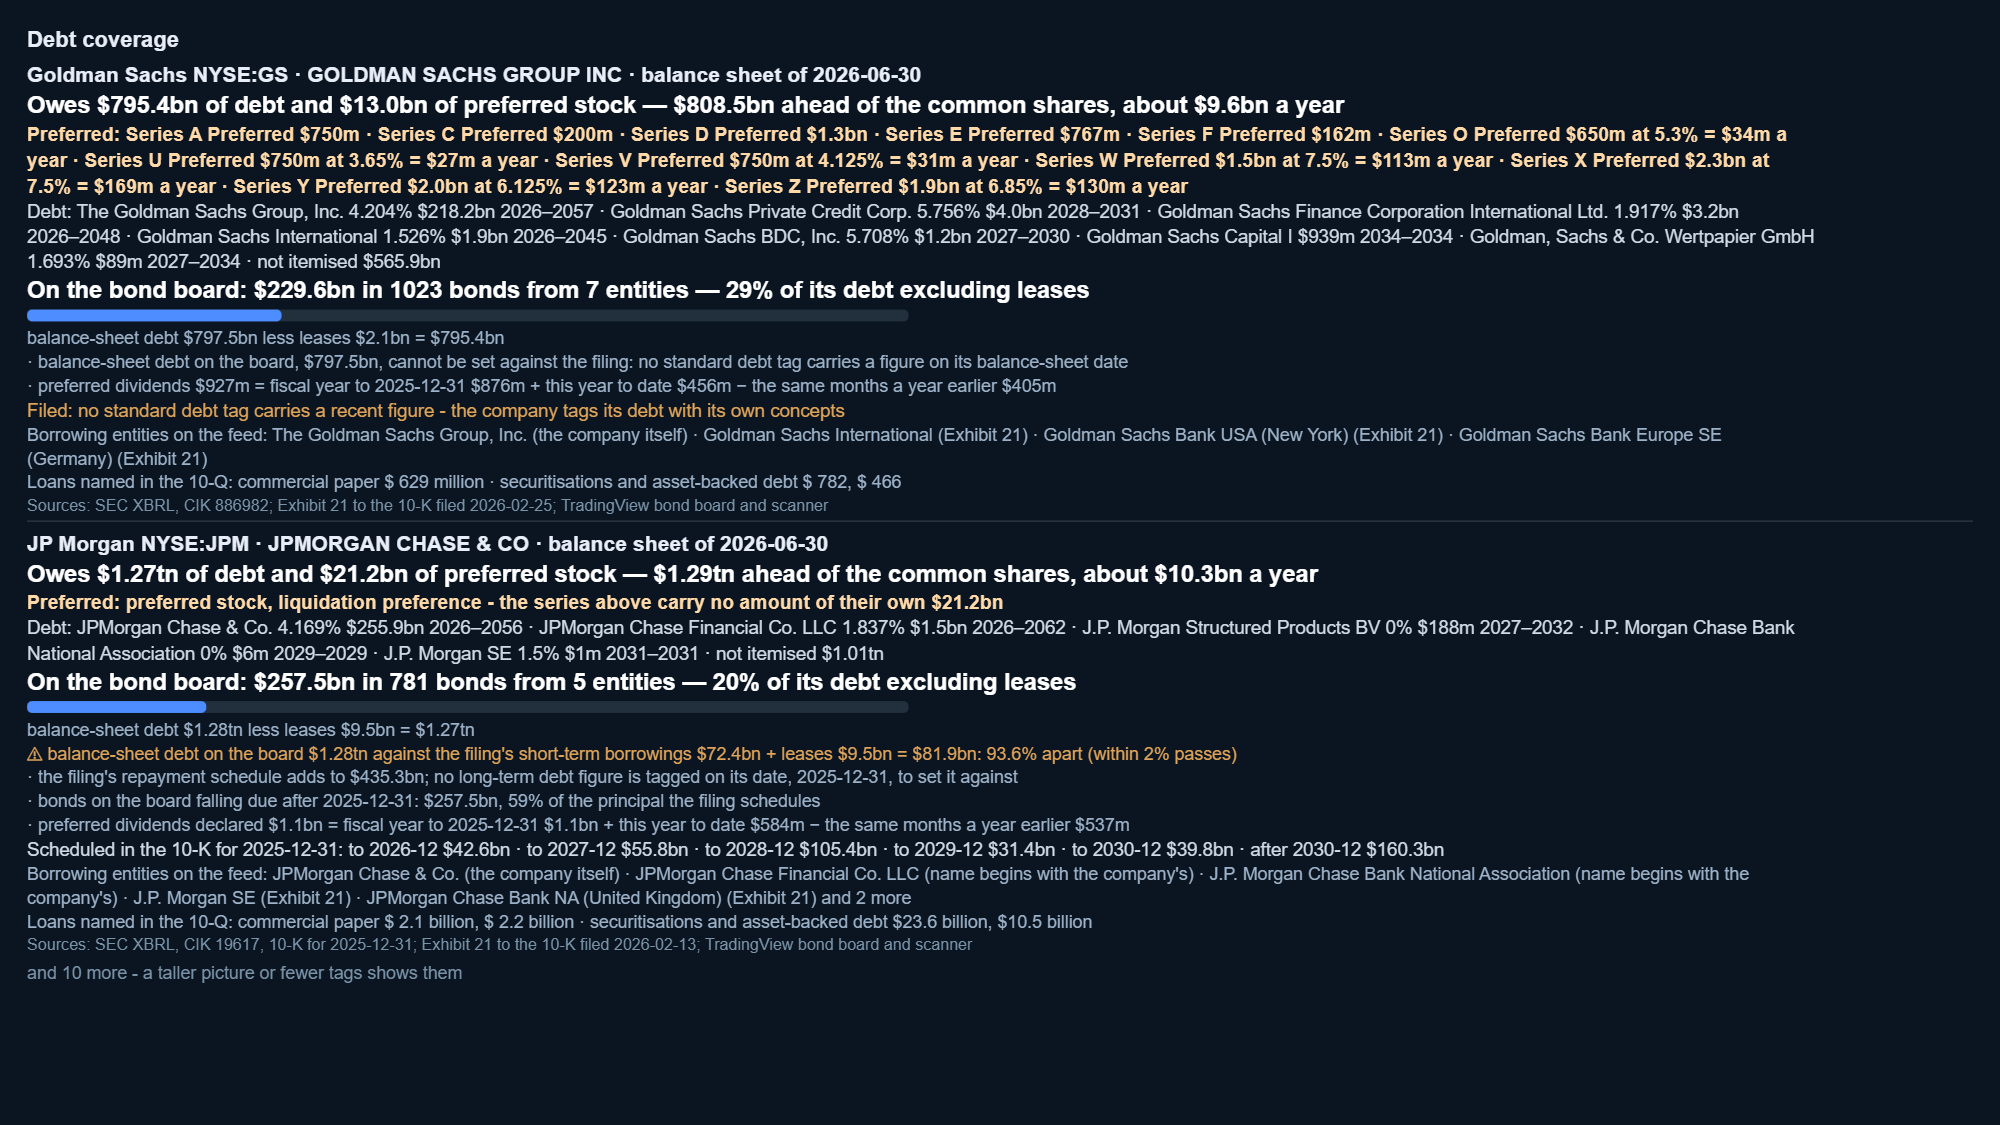
Debt coverage
Everything the company owes, in one table, read from its own filings: listed bonds, bank loans, leases and preferred stock series by series — with how much of the reported total the listed bonds actually account for.
From the filing's own XBRL instance, which is the only place a preferred series' liquidation preference or a single loan's balance exists at all.
Names what is missing — debt on the balance sheet that no listed bond explains — rather than quietly reporting only what it can see.
Cross-checked against the feed's total debt, leases included, so the two numbers are reconciled in front of you.
Not published yet — picture: debt coverage
6 of 7
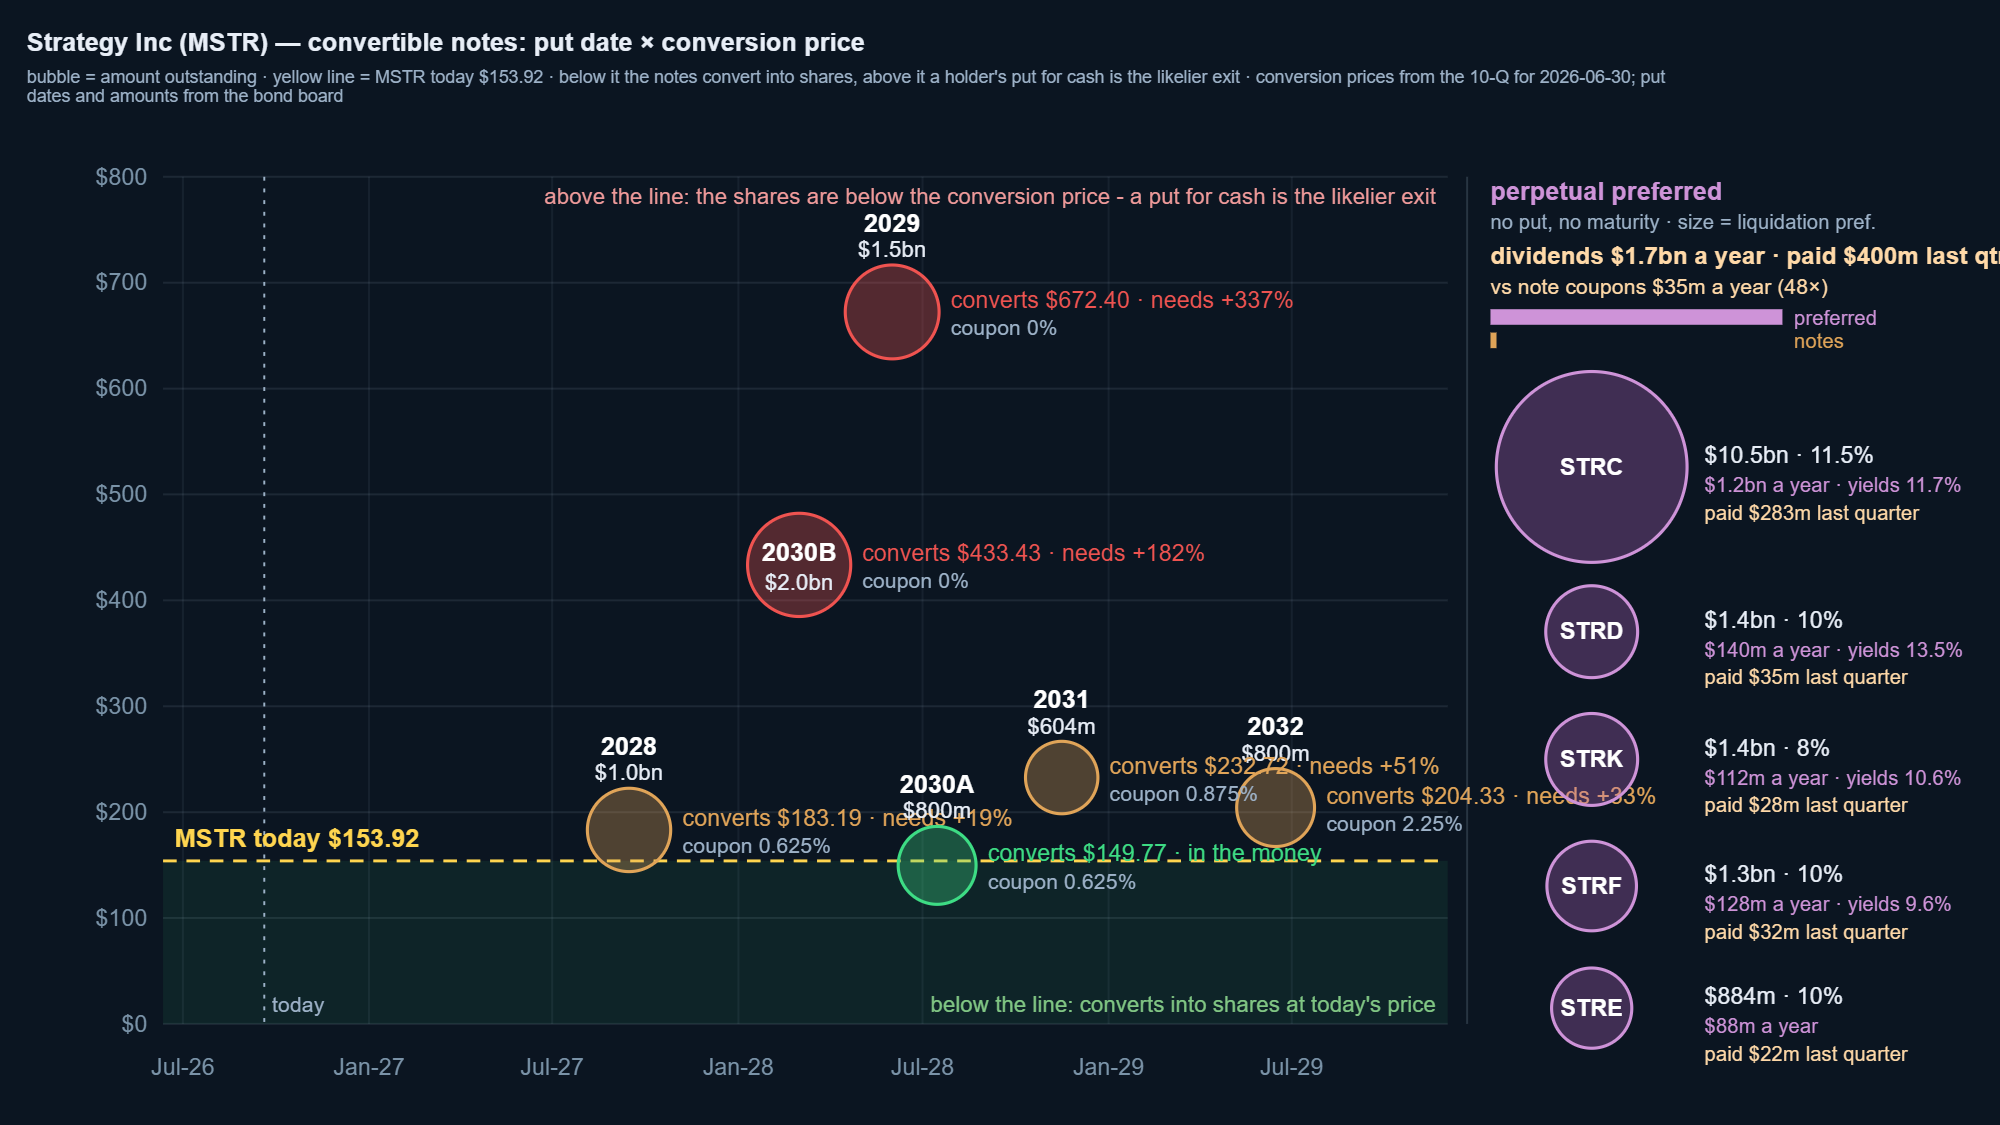
The convertible put wall
Each convertible note as a bubble at the date holders can put it back and the price it converts at, sized by what is outstanding, with the share price drawn across them. Where a bubble sits against that line is whether the note is heading for shares or for cash.
Conversion price per note, read from the filing rather than assumed from the year in its name.
Preferred series sit on the same picture, with what they actually pay, since a dividend nobody can stop is debt in everything but name.
Coupons and the cash cost beside each other, so a 0% convertible and a 6% preferred can be compared at all.
Not published yet — picture: convertible put wall
7 of 7
Private credit
Borrowing that never reaches a bond screen — term loans, direct lending, preferred paper — beside the listed lenders whose own books are the only place that market can be measured from outside.
Two questions, one panel: what this company borrows privately, and what the private credit market itself is doing.
Measured through listed vehicles, whose NAV, leverage and share price are public even when their loans are not.
Add your own tickers to the table when the ones that matter to you are not on it.
Not published yet — picture: private credit
The filings, not a summary of them
Per-instrument figures come from the filing's own XBRL instance, where the amounts sit on
their dimensions — which is the only place a preferred series' liquidation preference or a
single loan's balance exists at all.
Spread against the right curve
A euro bond is measured against a euro government curve, never a Treasury one, so a borrower
is not made to look cheap by the currency it happens to issue in.
Checkable, and exportable
Every panel exports both ways: as the picture, and as the rows behind it, so the arithmetic
can be redone rather than trusted.
Inside the app · 8 of many
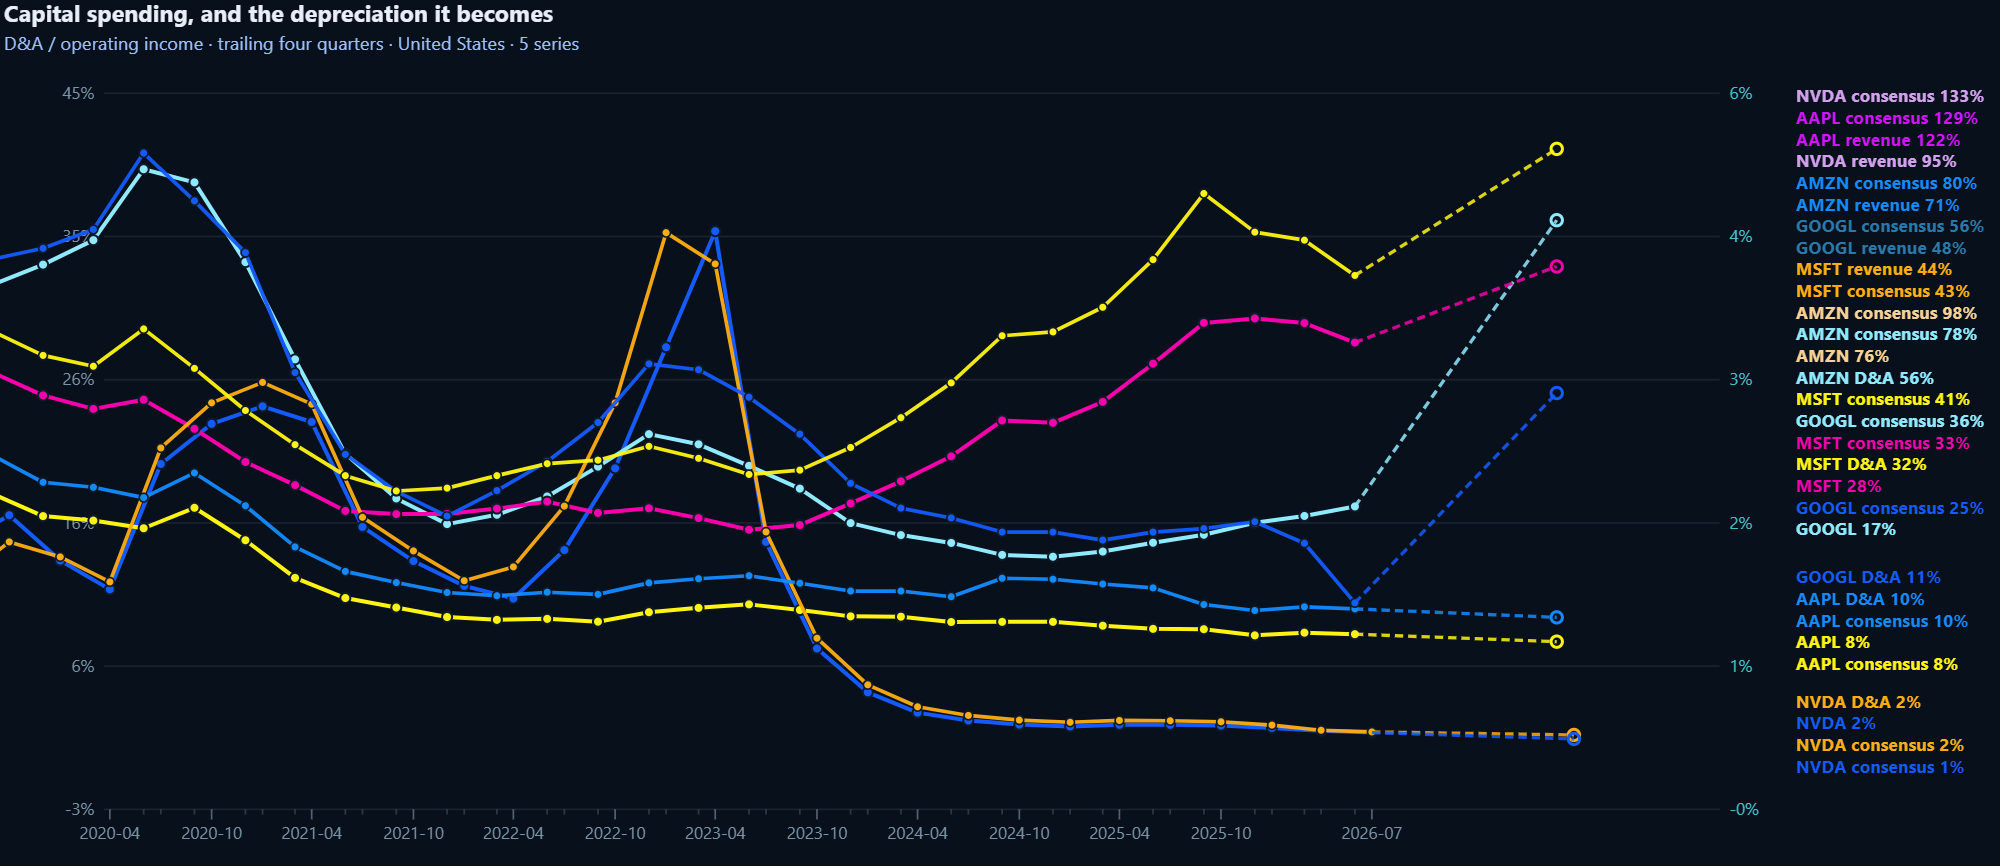
Capital spending, and the depreciation it becomes
A cheque written today is an expense spread over the years the company assumes the asset will
last. Two questions follow: how much of what a company earns is already spoken for by
yesterday's spending, and whether the spending is still running ahead of the charge.
Exported with the page's own Copy snapshot button.
Not published yet — open the capex page and press Publish.
The charge, derived and checked
Depreciation is taken as EBITDA minus operating income and checked against the reported
line wherever the feed carries one — and where the identity cannot hold, the page says so
rather than printing half of it.
Banks are left out, deliberately
Interest is a bank's revenue, not a cost to add back, so no depreciation can be derived for
them. They are named and excluded instead of quietly counted as zero.
Project the charge forward
Set asset lives, the share that is short-lived, the lag from spending to charge and the
growth you expect — and watch what today's capital spending does to tomorrow's earnings.
One company or the whole market
Tag a name to follow it quarter by quarter against consensus, or leave it off and read the
market as a single trailing line.